
A crown fractures three weeks after delivery. The patient's dentist blames your lab. Your insurer starts asking questions you weren't prepared for: Was it a design flaw or a material defect? Did the dentist approve the specifications? Does your policy even cover this type of claim? The distinction between professional liability and products liability for dental labs isn't just academic - it determines who pays, how much, and whether your coverage actually kicks in. With the digital dentistry market expanding at an 11% annual growth rate and projected to exceed $15 billion by 2027, the volume and complexity of claims against labs are growing in parallel. Understanding where design errors end and fabrication defects begin - and where your insurance might leave you exposed - is essential for any lab owner who wants to stay in business.
The Intersection of Professional and Products Liability in Dental Labs
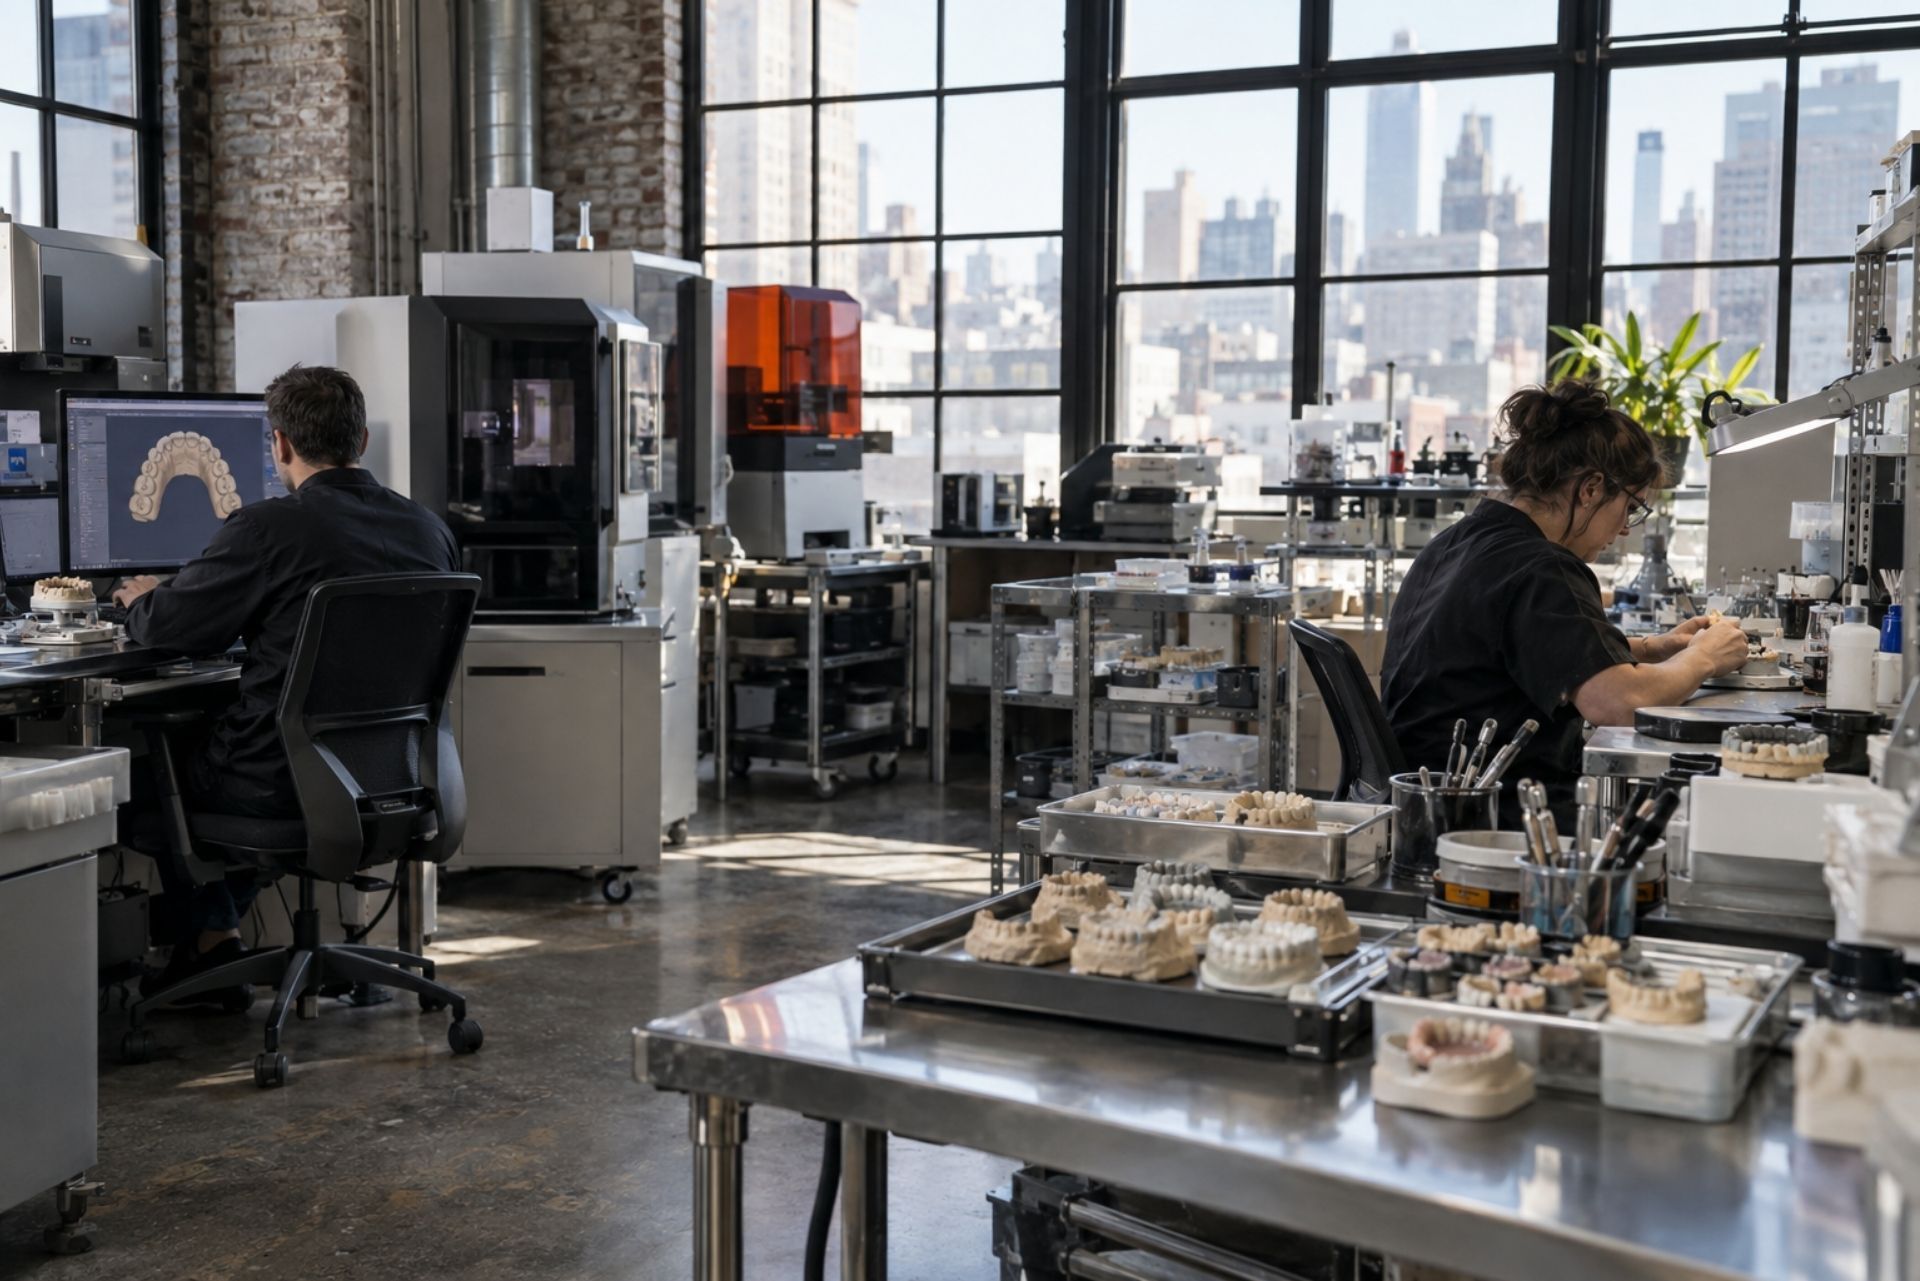
Dental labs occupy an unusual legal position. You're part manufacturer, part professional service provider, and the line between those roles blurs constantly. A single restoration can trigger both professional liability and products liability claims depending on what went wrong and how a plaintiff's attorney frames it.
This dual exposure creates real confusion during claims. A lab technician who designs a bridge using digital impressions is providing a professional service. That same lab, when it mills and ships the finished product, is acting as a manufacturer. Courts don't always agree on where one role ends and the other begins, which means your insurance needs to cover both angles or you're gambling.
Defining Professional Liability: When Design Goes Wrong
Professional liability (sometimes called errors and omissions, or E&O) covers mistakes in judgment, planning, and design. If your technician misreads a prescription, selects the wrong shade, or designs a framework with inadequate support structure, that's a professional error.
These claims hinge on whether you met the standard of care expected of a competent dental lab professional. Think of it as the "thinking" side of your work: the decisions you make before anything gets fabricated. A poorly planned occlusal scheme that causes TMJ issues, for example, falls squarely into professional liability territory. So does failing to flag a prescription that doesn't make clinical sense.
Defining Products Liability: Material Defects and Manufacturing Flaws
Products liability applies when the finished restoration itself is defective - regardless of whether anyone made a bad decision. A zirconia crown that cracks because of a porosity issue in the milling block is a product defect. An allergic reaction caused by undisclosed nickel content in an alloy is a product defect.
The key difference: products liability often doesn't require proving negligence. Under strict liability doctrine in many states, the lab can be held responsible simply because the product was defective and caused harm. You don't need to have done anything "wrong" in the traditional sense. The product just needs to have failed. That's a higher bar of exposure than most lab owners realize, and
dental malpractice premiums are climbing in 2026 partly because of this expanding risk.
Key Differences: Liability Breakdown Table
| Factor | Professional Liability (E&O) | Products Liability |
|---|---|---|
| What It Covers | Design errors, prescription misinterpretation, shade selection mistakes | Material defects, manufacturing flaws, contamination |
| Legal Standard | Negligence (failure to meet standard of care) | Often strict liability (no negligence required) |
| Trigger | A decision or judgment error | A defective finished product |
| Common Examples | Wrong bite registration, poor framework design | Cracked zirconia, allergic reaction to undisclosed alloy |
| Who Files Claims | Dentists, patients | Patients, dentists, sometimes insurers via subrogation |
| Typical Policy | Professional liability / E&O policy | Commercial general liability (CGL) or product liability rider |
| Statute of Limitations | Varies by state; often 2-3 years from discovery | Varies; some states allow claims years after delivery |
This table highlights why a single policy rarely covers everything. You need both types of protection working together.
Common Claims: Design Errors vs. Fabrication Defects
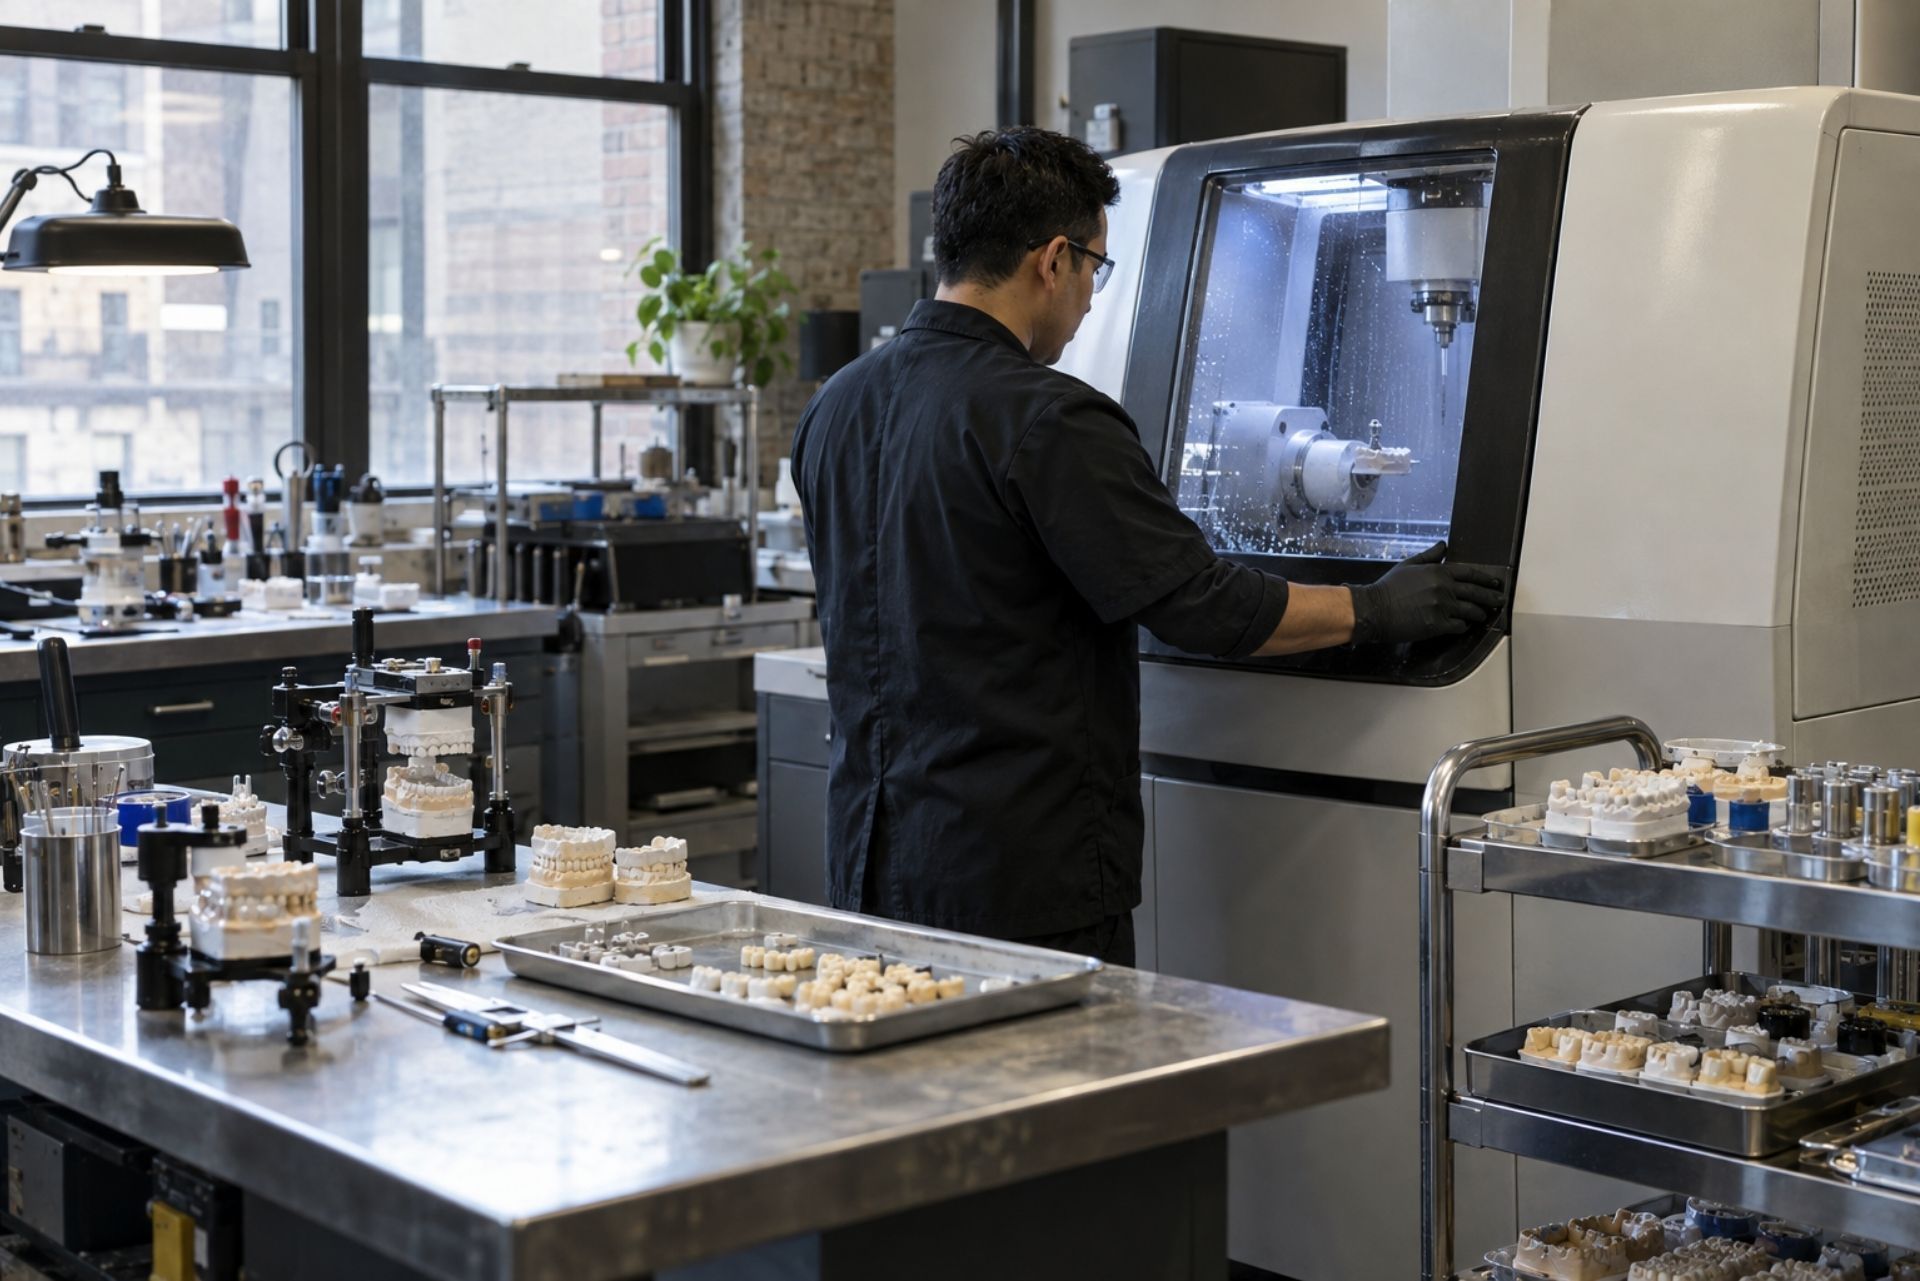
Most claims against dental labs fall into two buckets, and the distinction matters for your defense strategy. Design errors involve choices - selecting materials, interpreting prescriptions, planning restorations. Fabrication defects involve execution - how the product was actually made.
A lab that designs a three-unit bridge with insufficient connector width made a design error. A lab that designs the bridge correctly but ships it with a void in the solder joint has a fabrication defect. Same bridge, completely different liability analysis. Your defense and your coverage path diverge depending on which category applies.
CAD/CAM Software and Digital Impressions: Who Is Liable?
Digital workflows complicate liability significantly. If your CAD software auto-nests a crown and the algorithm creates an undersized margin, is that your error or the software vendor's? Labs increasingly rely on digital design tools and AI-assisted workflows that make decisions autonomously.
Here's the practical problem: most software licenses include liability disclaimers that push responsibility back onto the lab. You're the one who hit "send to mill." Courts have generally held that the lab, as the entity delivering the final product, bears responsibility for quality control - even when software contributed to the error. If you're using digital impressions sent by a dentist and those impressions are flawed, documenting your acceptance criteria becomes your best defense.
Material Failure: Allergic Reactions and Structural Breakage
Material-related claims are rising as labs work with a broader range of alloys, ceramics, and polymers. A patient who develops contact dermatitis from a cobalt-chromium framework has a products liability claim. A lithium disilicate crown that fractures under normal occlusal forces within weeks of cementation points to either a material defect or a fabrication issue.
Your documentation matters enormously here. Keeping lot numbers, material certificates of conformity, and firing logs can shift liability to the material manufacturer if the defect originated in their product. Without that paper trail, you absorb the full claim. Labs that track materials meticulously settle claims faster and pay less.
Most dental labs carry some form of general liability insurance and assume they're covered. They're often wrong. Standard commercial general liability (CGL) policies are built for slip-and-fall accidents and property damage - not for the specialized risks labs face daily.
The gap between what you think you're covered for and what your policy actually pays out is where labs get hurt. A $2 million CGL policy might not pay a dime on a claim involving a design error because the policy excludes professional services. You need to read the exclusions, not just the declarations page.
The 'Professional Services' Exclusion in General Liability
This is the single most common coverage gap in dental lab insurance. Your CGL policy likely contains an exclusion for "professional services," which means any claim arising from your expertise, judgment, or design work gets denied. The insurer will argue that designing a restoration is a professional service, not a products liability event.
That leaves you needing a separate professional liability policy to fill the gap. Some labs discover this only after a claim is filed, which is the worst possible time. If your CGL and E&O policies come from different carriers, coordination problems can also arise - each insurer pointing to the other as the responsible party. Bundled policies from the same carrier reduce this risk, though they cost more upfront.
Cyber Liability and Digital Patient Data Risks
As labs handle digital impressions, patient records, and HIPAA-protected information, cyber liability becomes a real exposure. A data breach involving patient scans or prescription records triggers notification requirements, potential fines, and lawsuits that neither your CGL nor your professional liability policy covers.
Dental labs processing digital files are increasingly adopting cloud-based platforms that create new attack surfaces. A standalone cyber liability policy - or a cyber endorsement on your existing coverage - is no longer optional for labs handling digital patient data. Premiums for small labs typically run $500 to $2,000 annually, which is trivial compared to the cost of a single breach notification.
Defense Strategies for Dental Technicians and Lab Owners
Strong documentation is your first line of defense. Every prescription should be logged with the date received, any clarifications requested, and the dentist's approval of the design. If a claim arises, this paper trail establishes that you followed the dentist's instructions or flagged concerns in writing.
Quality control protocols matter just as much. Calibrate your equipment on schedule. Keep firing and milling logs. Photograph restorations before shipping. These steps cost almost nothing but can make the difference between a dismissed claim and a six-figure settlement. Labs that implement ISO 13485-aligned quality systems see fewer claims and lower premiums over time.
Contractual risk transfer is another tool. Your terms of service with dentist clients should include clear language about prescription responsibility, approval workflows, and dispute resolution. An indemnification clause that holds the prescribing dentist responsible for clinical decisions they approve can shift significant liability away from your lab.
Common Questions About Dental Lab Insurance
Does my general liability policy cover a defective crown claim? It depends on the cause. If the claim involves a material defect, your CGL might respond. If it involves a design error or professional judgment, you'll likely need a separate E&O policy. Check your exclusions carefully.
Can a patient sue my lab directly, or only the dentist? Patients can and do sue labs directly, especially under products liability theories. You don't need a direct relationship with the patient to be named in a lawsuit.
How much does professional liability insurance cost for a small dental lab? Premiums vary by state, revenue, and claims history, but most small labs pay between $1,200 and $4,000 per year for E&O coverage. Premiums have been climbing in 2026 due to increased digital workflow claims.
What's the difference between "claims-made" and "occurrence" policies? A claims-made policy covers you only if the claim is filed while the policy is active. An occurrence policy covers any incident that happened during the policy period, even if the claim comes years later. Occurrence policies cost more but offer broader protection.
Do I need cyber liability insurance if I only receive digital impressions? Yes. Any lab receiving, storing, or transmitting patient data has HIPAA obligations. A breach - even an accidental one - can trigger fines and lawsuits your other policies won't cover.
Should I carry the same coverage limits as my dentist clients? Not necessarily, but your limits should reflect your revenue and risk exposure. Most labs carry $1 million per occurrence and $2 million aggregate as a starting point.
Protecting Your Lab's Future
The gap between professional liability and products liability isn't a technicality - it's the fault line where dental labs lose money, reputation, and sometimes their business. Design errors and fabrication defects trigger different legal theories, different defenses, and different insurance responses. A single policy rarely covers both.
Your action items are straightforward: audit your current policies for professional services exclusions, confirm you have both E&O and products liability coverage, add cyber liability if you handle any digital patient data, and document everything from prescriptions to material lot numbers. Talk to a broker who understands dental lab exposures specifically - not just general small business insurance.
The labs that survive claims aren't necessarily the ones that never make mistakes. They're the ones whose coverage actually responds when something goes wrong.
ABOUT THE AUTHOR:
TAYLOR RICHARDSON
Taylor Richardson is the founder and CEO of 5M Insurance. With a focus on real estate risk management, Taylor helps investors and property managers nationwide secure smarter, scalable coverage solutions—without the headaches of traditional insurance brokers.
Contact Us
Comprehensive Coverage for Businesses of All Sizes
Protecting Your Business, Securing Your Future
General Liability Insurance
Protection against lawsuits and third-party claims.
Workers Comp Insurance
Required protection for employees in case of injury or illness.
Commercial Property Insurance
Coverage for buildings, equipment, and business assets.
Commercial Auto Insurance
Coverage for company vehicles and fleet operations.
Commercial Umbrella Insurance
Protection against errors, omissions, and negligence claims.
Business Owner's Policy
A bundled policy combining essential business coverages.
Personalized Insurance for Every Stage of Life
Protect What Matters Most with Comprehensive Coverage
Jewelry Insurance
Specialized protection for valuable items like engagement rings, watches, and heirlooms.
Pet Insurance
Financial protection for veterinary care and unexpected pet health expenses.
Specialized Insurance for Your Business Needs
Serving the Industries That Drive
New York & New Jersey
What Our Clients Say
Trusted by Businesses & Families Across New York & New Jersey
Frequently Asked Questions
Get Answers to Your Insurance Questions
We understand that insurance can be complex. Here are answers to some of the most common questions our clients ask. If you need more information, our team is always here to help.
- Still have questions?
How do I know what coverage I need?
Choosing the right insurance starts with understanding your risks. For personal insurance, consider factors like your home’s value, your vehicle, and your financial responsibilities. Homeowners may need additional protection for floods or valuable belongings, while drivers should evaluate coverage limits based on their assets.
For businesses, the right coverage depends on the industry, number of employees, and liability risks. General liability is essential for most businesses, but some may need property, workers’ compensation, or business owner’s policies. Our team can assess your needs and guide you to the best options.
What factors affect my insurance rate?
Insurance rates are influenced by multiple factors. For auto policies, your driving history, vehicle type, and location play a major role. Home insurance costs depend on your home’s value, construction type, and potential risks like flooding or fire hazards.
For business insurance, rates vary based on the industry, size, claims history, and coverage limits. High-risk industries may require specialized policies, while businesses with strong safety measures and claims-free histories can qualify for better rates. Our agents help find discounts and cost-saving opportunities.
Why should I work with an independent insurance agency?
Unlike captive agents who represent a single insurance company, independent agencies like Joyce Insurance Agency work with multiple carriers to find the best coverage for your needs. This means you get more choices, competitive rates, and a policy that truly fits your situation.
We take the time to understand your needs, compare options, and provide expert advice. Whether you're insuring your home, car, or business, our priority is finding you the best protection at a great value.
How quickly can I get insured?
The time it takes to secure a policy depends on the type of insurance. Auto and home policies can often be issued the same day, while business insurance may take longer, especially for specialized coverage. Workers’ compensation and commercial policies may require underwriting approval, which can extend the timeline.
We prioritize efficiency and make the process as smooth as possible. Once we understand your needs, we work quickly to get you insured with minimal hassle.
What should I do if I need to file a claim?
If you need to file a claim, contact us as soon as possible. We’ll guide you through the process and ensure you have everything needed to submit your claim correctly. Gathering necessary documentation, such as photos, receipts, or witness statements, can help speed up the process.
We work directly with your insurance provider to streamline communication and advocate on your behalf. Our goal is to make sure your claim is handled quickly and fairly so you can recover without unnecessary stress.
How can I lower my insurance costs?
There are several ways to reduce insurance premiums without sacrificing coverage. For auto insurance, maintaining a clean driving record, bundling policies, and increasing deductibles can help lower costs. Homeowners can save by installing security systems, upgrading safety features, and bundling home and auto policies.
For business owners, implementing risk management strategies, maintaining a claims-free history, and working with an independent agent to find competitive rates can lead to cost savings. Our team helps you explore discounts and options to ensure you’re getting the best value.
Contact Us
Phone
Location