
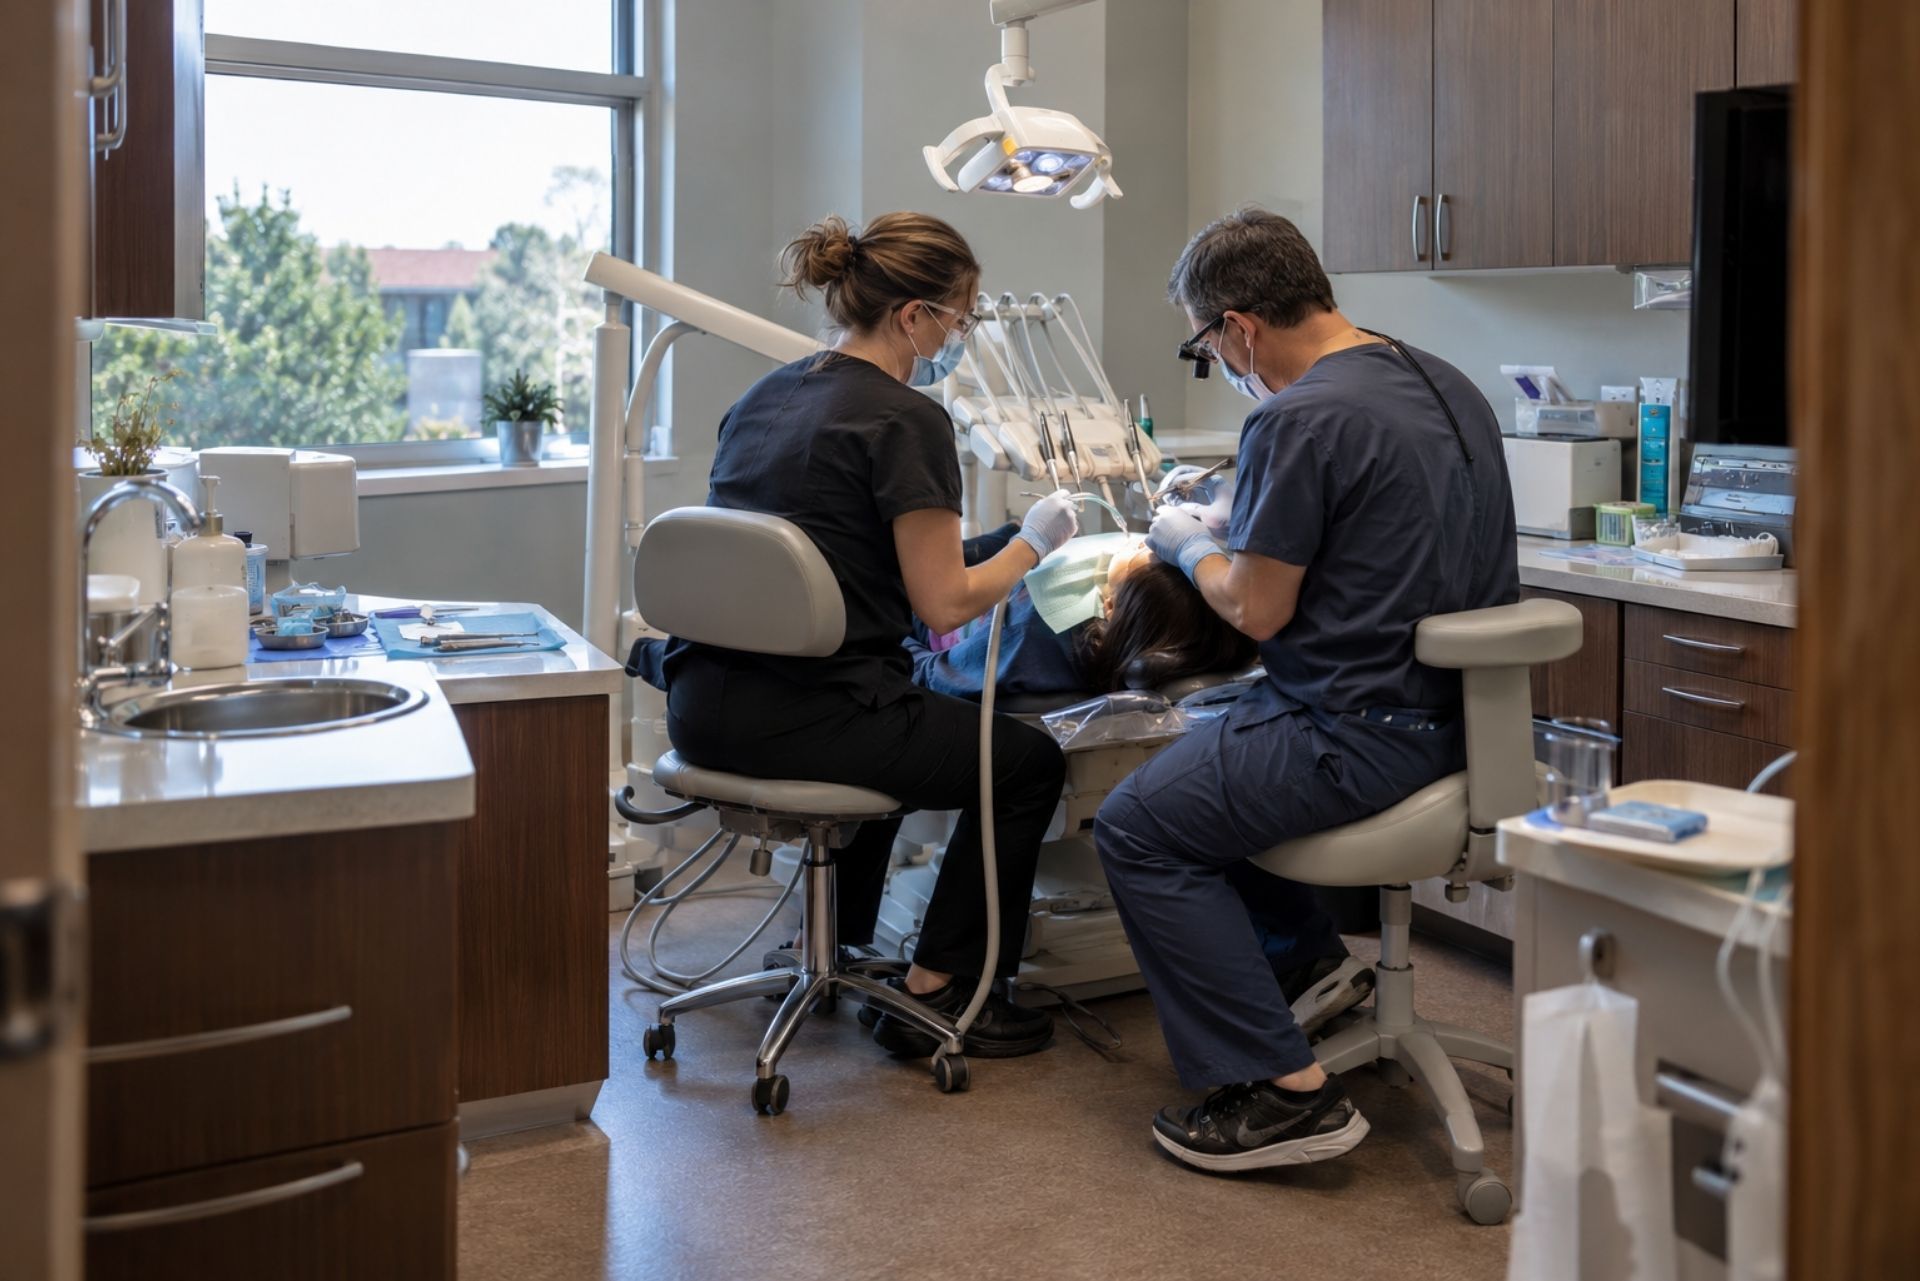
A dental hygienist develops carpal tunnel after years of scaling. A dental assistant gets stuck by a contaminated needle during a restorative procedure. The front desk coordinator trips over a box of supply shipments in the hallway. Each of these scenarios triggers a workers' compensation claim, and each one plays out differently on your premium statement. Workers' compensation for dental offices covers a surprisingly wide range of injuries, from needlesticks and repetitive strain to slips in the sterilization area. But the claims themselves are only half the equation. How you classify your employees, organize your payroll records, and respond to your annual audit determines whether you're paying a fair premium or hemorrhaging money on preventable surcharges.
Dental practices tend to be small businesses, often with fewer than fifteen employees, which means a single mishandled claim can spike your experience modification rate for years. The risks aren't hypothetical either. Repetitive strain is the
most frequent type of workers' comp claim in dental offices, outpacing even sharps injuries. And with an aging workforce driving up claim severity, the financial exposure keeps growing. This guide walks you through the specific hazards your staff faces, the claims process, audit preparation, and practical steps to keep your practice protected.
Understanding Workers' Comp in the Dental Industry
Workers' compensation insurance isn't optional for dental practices in most states. It exists to cover medical expenses, lost wages, and rehabilitation costs for employees injured on the job, regardless of fault. For dental offices, the risk profile is distinct from general healthcare because the work involves prolonged static postures, frequent exposure to sharps, and daily contact with chemical agents like disinfectants and impression materials.
Your premium is calculated based on payroll, employee classification codes, and your claims history. A clean record keeps costs down. A pattern of claims, even minor ones, pushes your experience modifier above 1.0, and that means higher premiums for three or more years.
Common Workplace Hazards for Dental Staff
The hazards in a dental office break down into a few main categories. Ergonomic injuries dominate: hygienists and assistants spend hours in awkward positions, often hunched over patients with limited range of motion. Roughly one-third of all dental hygienists report musculoskeletal symptoms that negatively affect their daily production levels.
Needlestick and sharps injuries remain a constant concern, particularly during instrument transfer and cleanup. Chemical exposure is another risk. As of July 20, 2026, dental practices must complete mandatory staff training on new GHS-compliant labeling and updated Safety Data Sheets to comply with the federal Hazard Communication Standard overhaul. Slip-and-fall incidents round out the list, often caused by wet floors in sterilization areas or cluttered storage rooms.
Legal Requirements for Practice Owners
Most states require workers' comp coverage as soon as you hire your first employee. A few states set the threshold at three to five employees, but don't gamble on that distinction without checking your state's specific statute. Penalties for non-compliance range from fines to criminal charges, and in some states, an uninsured employer becomes personally liable for all injury costs.
You're also required to post notices informing employees of their rights, maintain an OSHA 300 log of recordable injuries, and report certain incidents within strict timeframes. Failing to carry coverage doesn't just expose you to lawsuits: it can jeopardize your dental license and your ability to participate in insurance networks.
A well-managed claim costs less than a poorly managed one. That's not a cliché: it's a financial reality. The strongest claims organizations are distinguished by what happens after an incident lands on their desks, not by avoiding incidents entirely. Your response in the first 24 to 48 hours shapes the trajectory of the entire claim.
Immediate Steps After a Needle Stick or Injury
For a needlestick, the protocol is clinical and time-sensitive:
- Wash the wound immediately with soap and water (don't squeeze the puncture site).
- Report the incident to the practice owner or office manager.
- Identify the source patient and initiate post-exposure evaluation, including baseline blood draws for both the employee and the source patient when consent is obtained.
- Refer the injured employee to the designated workers' comp treating physician, not their personal doctor, unless your state allows employee choice of provider.
For ergonomic injuries, the onset is usually gradual. Encourage employees to report symptoms early, before they become disabling. A wrist splint and modified duties cost far less than a carpal tunnel surgery claim.
Reporting Timelines and Documentation
Every state sets its own reporting deadline, but most require the employer to file a First Report of Injury within three to seven business days. Missing that window can result in penalties and complicate the claim.
Document everything from the start. Take photos of the incident location if relevant. Collect written statements from the injured employee and any witnesses. Keep copies of the employee's job description and any modified duty assignments. This documentation protects you if the claim is disputed and gives your insurer the information they need to manage it efficiently.
Your workers' comp premium is an estimate when the policy begins. The annual audit reconciles that estimate with your actual payroll and employee classifications. If your payroll grew or your staff classifications were wrong, you'll owe additional premium. If payroll shrank, you might get a refund.
Auditors aren't adversaries, but they will catch mistakes. The most common errors in dental offices involve misclassifying employees and failing to separate payroll by job function.
Classifying Dental Hygienists vs. Clerical Staff
Class codes matter because they reflect risk. A dental hygienist performing clinical procedures carries a different risk profile than a receptionist answering phones. If you lump everyone under one code, you're either overpaying for low-risk employees or underpaying for high-risk ones, and underpayment triggers audit surcharges.
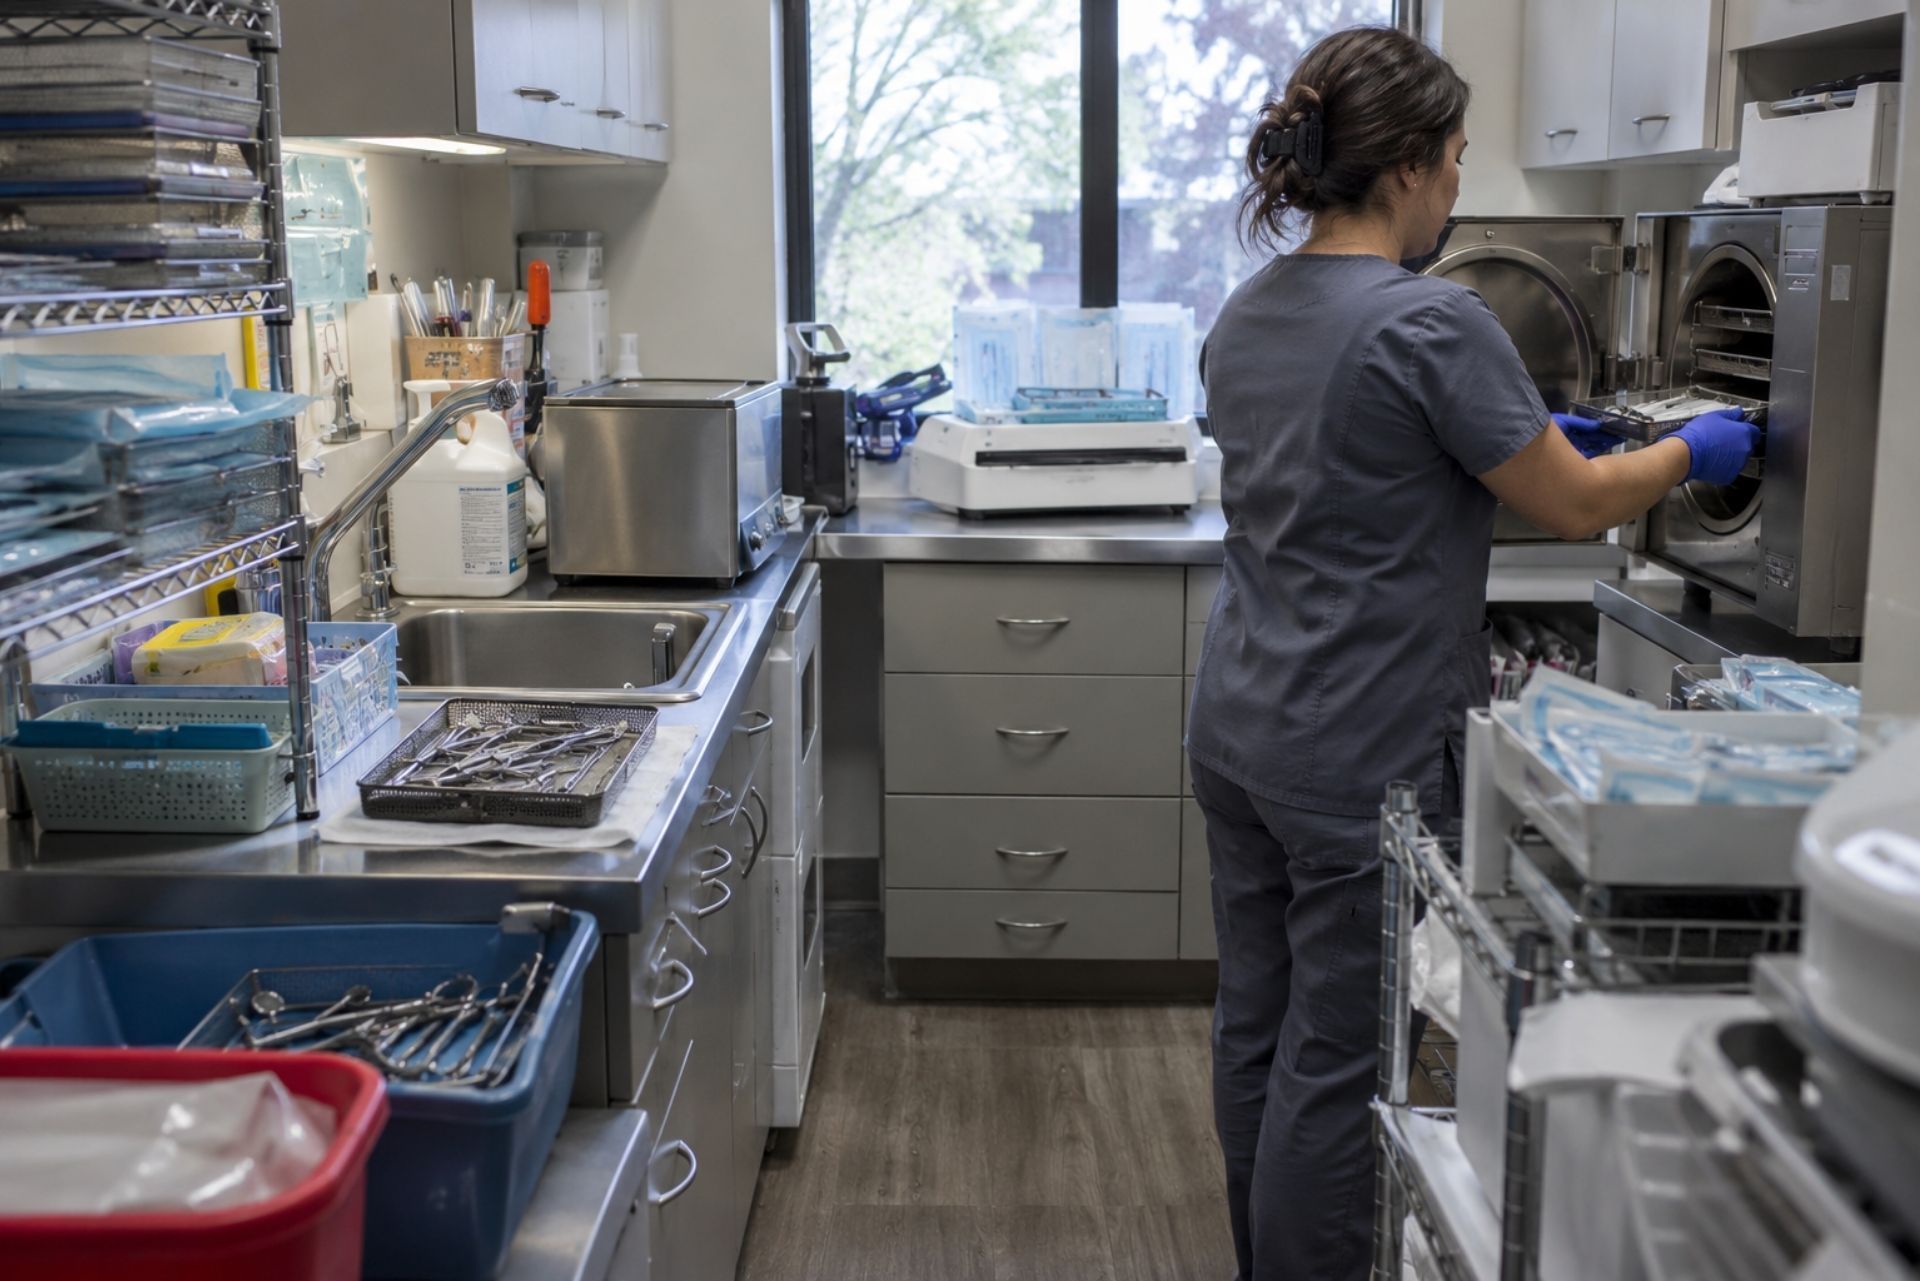
Typical class codes for dental offices include a clinical code for dentists, hygienists, and assistants, and a clerical code for front desk and billing staff. Some states also have a separate code for dental lab technicians. Make sure your payroll system tracks hours and wages by job function, not just by employee name. An employee who splits time between clinical and administrative duties should have their payroll allocated proportionally.
Organizing Payroll Records and Subcontractor Certificates
Before your audit, gather these records:
- Quarterly payroll reports (state and federal)
- Year-end W-2 summaries
- 1099 forms for any independent contractors
- Certificates of insurance for subcontractors (temporary staffing agencies, IT consultants, cleaning services)
The subcontractor piece trips up a lot of dental offices. If you hire a temp hygienist through a staffing agency and that agency doesn't carry their own workers' comp, their payroll gets added to yours during the audit. The same applies to any 1099 worker without proof of coverage. Keep certificates of insurance on file for every contractor and verify they're current before the audit period ends.
Comparison: Incident Types and Coverage Impact
Not all claims affect your premium equally. The distinction between medical-only and lost-time claims is one of the most important factors in how your experience modification rate is calculated.
Medical-only claims, where the employee receives treatment but doesn't miss work beyond the day of injury, carry a reduced weight in most state rating formulas. Lost-time claims, where the employee misses days or weeks, carry full weight and drive your modifier up much faster.
Chart: Medical-Only vs. Lost-Time Claims
| Factor | Medical-Only Claims | Lost-Time Claims |
|---|---|---|
| Typical examples | Minor needlestick, small laceration, first-aid treatment | Carpal tunnel surgery, back injury requiring weeks off |
| Average cost range | Lower: often under a few thousand dollars | Higher: can reach tens of thousands or more |
| Impact on experience mod | Reduced weighting (in California, claims of $250 or less do not impact the calculation) | Full weighting of actual incurred cost |
| Return-to-work timeline | Same day or next day | Days to months |
| Best mitigation strategy | Prompt first aid, immediate reporting | Modified duty programs, early intervention |
This is why modified duty programs matter so much. Bringing an injured hygienist back on light duty, even if they're only doing patient charting or instrument organization, keeps the claim in the medical-only category and limits its impact on your premium.
One often-overlooked factor:
workers aged 55 and older account for 34% of workers' comp claim costs, with dental claims in that age bracket seeing significantly higher severity due to longer recovery times. If your practice has experienced staff members approaching retirement age, proactive ergonomic assessments and wellness programs aren't just kind: they're financially smart.
Common Questions About Dental Workers' Comp
Does workers' comp cover repetitive strain injuries even if they develop slowly over months or years? Yes. Repetitive strain injuries like carpal tunnel syndrome and tendinitis are compensable in every state, though you'll need medical documentation linking the condition to workplace duties. The claim filing process for cumulative trauma injuries varies by state.
What happens if an employee refuses to file a claim after a needlestick? You should still document the incident and follow your exposure control plan. Some states require employer reporting regardless of whether the employee files a formal claim. Failing to document a needlestick can create OSHA compliance problems.
Can I use a PEO or staffing agency to handle workers' comp for my dental office? You can, and many small practices do. Just verify that the PEO's policy actually covers your clinical staff under the correct class codes. Some PEO arrangements leave gaps that only surface during an audit or a claim.
Are dental practice owners covered under their own workers' comp policy? It depends on your state and your business structure. Sole proprietors and partners can usually elect to exclude themselves. Corporate officers in some states are automatically included unless they file an exclusion. Check your state's rules, because opting out means you have no wage replacement if you're injured.
How often should I review my class codes and payroll allocations? At least annually, ideally before your policy renewal. Any time you hire a new role or an employee's duties change significantly, update your classifications with your insurer.
Protecting Your Practice for the Long Term
Workers' compensation for dental offices involves more moving parts than most practice owners realize. Between needlestick protocols, repetitive injury prevention, payroll classification, and audit preparation, there's a lot to manage. But the practices that handle claims well and maintain accurate records consistently pay lower premiums over time.
Start with the basics: train your staff on injury reporting procedures, maintain a modified duty program, and keep your payroll records clean and organized by job function. Review your class codes annually and collect certificates of insurance from every subcontractor before they set foot in your office.
The cost of getting this wrong isn't just a higher premium. It's the disruption of losing a skilled hygienist to a preventable injury, the stress of an audit surcharge you didn't see coming, and the legal exposure of being caught without proper coverage. Build your safety culture now, document everything, and treat your workers' comp program as what it is: a core part of running a responsible dental practice.
ABOUT THE AUTHOR:
TAYLOR RICHARDSON
Taylor Richardson is the founder and CEO of 5M Insurance. With a focus on real estate risk management, Taylor helps investors and property managers nationwide secure smarter, scalable coverage solutions—without the headaches of traditional insurance brokers.
Contact Us
Comprehensive Coverage for Businesses of All Sizes
Protecting Your Business, Securing Your Future
General Liability Insurance
Protection against lawsuits and third-party claims.
Workers Comp Insurance
Required protection for employees in case of injury or illness.
Commercial Property Insurance
Coverage for buildings, equipment, and business assets.
Commercial Auto Insurance
Coverage for company vehicles and fleet operations.
Commercial Umbrella Insurance
Protection against errors, omissions, and negligence claims.
Business Owner's Policy
A bundled policy combining essential business coverages.
Personalized Insurance for Every Stage of Life
Protect What Matters Most with Comprehensive Coverage
Jewelry Insurance
Specialized protection for valuable items like engagement rings, watches, and heirlooms.
Pet Insurance
Financial protection for veterinary care and unexpected pet health expenses.
Specialized Insurance for Your Business Needs
Serving the Industries That Drive
New York & New Jersey
What Our Clients Say
Trusted by Businesses & Families Across New York & New Jersey
Frequently Asked Questions
Get Answers to Your Insurance Questions
We understand that insurance can be complex. Here are answers to some of the most common questions our clients ask. If you need more information, our team is always here to help.
- Still have questions?
How do I know what coverage I need?
Choosing the right insurance starts with understanding your risks. For personal insurance, consider factors like your home’s value, your vehicle, and your financial responsibilities. Homeowners may need additional protection for floods or valuable belongings, while drivers should evaluate coverage limits based on their assets.
For businesses, the right coverage depends on the industry, number of employees, and liability risks. General liability is essential for most businesses, but some may need property, workers’ compensation, or business owner’s policies. Our team can assess your needs and guide you to the best options.
What factors affect my insurance rate?
Insurance rates are influenced by multiple factors. For auto policies, your driving history, vehicle type, and location play a major role. Home insurance costs depend on your home’s value, construction type, and potential risks like flooding or fire hazards.
For business insurance, rates vary based on the industry, size, claims history, and coverage limits. High-risk industries may require specialized policies, while businesses with strong safety measures and claims-free histories can qualify for better rates. Our agents help find discounts and cost-saving opportunities.
Why should I work with an independent insurance agency?
Unlike captive agents who represent a single insurance company, independent agencies like Joyce Insurance Agency work with multiple carriers to find the best coverage for your needs. This means you get more choices, competitive rates, and a policy that truly fits your situation.
We take the time to understand your needs, compare options, and provide expert advice. Whether you're insuring your home, car, or business, our priority is finding you the best protection at a great value.
How quickly can I get insured?
The time it takes to secure a policy depends on the type of insurance. Auto and home policies can often be issued the same day, while business insurance may take longer, especially for specialized coverage. Workers’ compensation and commercial policies may require underwriting approval, which can extend the timeline.
We prioritize efficiency and make the process as smooth as possible. Once we understand your needs, we work quickly to get you insured with minimal hassle.
What should I do if I need to file a claim?
If you need to file a claim, contact us as soon as possible. We’ll guide you through the process and ensure you have everything needed to submit your claim correctly. Gathering necessary documentation, such as photos, receipts, or witness statements, can help speed up the process.
We work directly with your insurance provider to streamline communication and advocate on your behalf. Our goal is to make sure your claim is handled quickly and fairly so you can recover without unnecessary stress.
How can I lower my insurance costs?
There are several ways to reduce insurance premiums without sacrificing coverage. For auto insurance, maintaining a clean driving record, bundling policies, and increasing deductibles can help lower costs. Homeowners can save by installing security systems, upgrading safety features, and bundling home and auto policies.
For business owners, implementing risk management strategies, maintaining a claims-free history, and working with an independent agent to find competitive rates can lead to cost savings. Our team helps you explore discounts and options to ensure you’re getting the best value.
Contact Us
Phone
Location