
A delivery van slides through a red light on Delaware Avenue during a January squall and T-bones a sedan. Your driver is fine, but the other motorist isn't, and the claim lands on your desk with medical bills attached. If that van was insured under someone's personal auto policy, you could be paying out of pocket. This guide covers
business insurance in Buffalo, NY, including general liability, property, commercial auto, workers' compensation, and
cyber coverage. It also explains what these policies cost and where local owners tend to get caught off guard.
Buffalo's insurance market doesn't behave like New York City's, and it shouldn't be priced like it. Upstate businesses generally pay less because of lower litigation frequency, lower property values, and smaller claim payouts. Median general liability costs for small service businesses in Buffalo and Upstate New York run around $540, compared to roughly $890 in the city.
The catch is that cheaper doesn't mean simpler. Buffalo carries risks that a Manhattan office tenant rarely thinks about:
- Lake-effect snow loads that can collapse flat commercial roofs
- Freeze-thaw cycles that burst sprinkler lines and crack parking lots, which leads to slip-and-fall claims
- Older building stock in neighborhoods like Black Rock and the East Side, where wiring and plumbing raise property rates
- Strict state mandates for workers' comp, disability, and Paid Family Leave that apply no matter where you operate
Here's what that means for you: shop locally, but buy coverage built for Western New York conditions rather than a generic national package.
Core Coverage: General Liability and Property Insurance
General liability (GL) pays for third-party bodily injury, property damage, and advertising injury claims. If a customer slips on slush tracked into your Elmwood Village boutique and fractures a wrist, GL covers their medical bills and your legal defense. It won't cover injuries to your own employees, damage to your own property, or professional mistakes. Those need workers' comp, property, and E&O policies.
Most Buffalo landlords require tenants to carry GL with $1 million per occurrence limits and to name the landlord as an additional insured. Read your lease before you buy. Many owners discover the additional insured requirement only after the landlord's property manager rejects their certificate.
A Business Owner's Policy (BOP) bundles GL and commercial property, usually at a lower price than buying each separately. For a small café or professional office, a BOP is often the most efficient starting point. Contractors, manufacturers, and businesses with heavy equipment typically outgrow BOP eligibility and need standalone policies.
Protecting Your Physical Assets from WNY Weather
Commercial property insurance covers your building, inventory, equipment, and furniture. In Buffalo, the details in the policy wording matter more than the headline limit.
Don'ts Checklist:
- Don't assume flood is covered. Standard property policies exclude flood. Businesses near the Buffalo River, Scajaquada Creek, or Lake Erie shoreline need separate flood coverage.
- Don't ignore the roof clause. Some carriers settle older roofs at actual cash value, not replacement cost. A 20-year-old roof collapsing under snow could leave you with a fraction of what you need to rebuild.
- Don't skip business income coverage. After the November 2022 storm, many closed businesses lost far more in revenue than in physical damage.
- Don't forget equipment breakdown. A frozen and cracked boiler is often excluded under basic forms.
For restaurant owners, spoilage coverage is worth adding. A two-day power outage during a winter storm can wipe out thousands of dollars in refrigerated inventory.
New York State Requirements: Workers' Comp and Disability
New York requires nearly every employer with one or more employees to carry three coverages: workers' compensation, disability benefits (DBL), and Paid Family Leave (PFL). This applies to part-time workers and family members on payroll in most cases. The Workers' Compensation Board can issue penalties for each 10-day period without coverage, and stop-work orders are common.
There's good news on pricing. Effective October 1, 2026, the state implemented a 22% average decrease in workers' compensation loss cost rates, projected to save policyholders an average of $1,779. Your actual savings depend on your class codes, payroll, and experience modification.
One thing to keep in mind is the assessment surcharge. For 2026, the New York workers' comp assessment rate is 7.0% of the standard premium, and it shows up as a separate line on your bill.
PFL is funded by employees through payroll deductions. The 2026 employee contribution is 0.432% of gross wages, capped at $411.91 per year. Employees on leave can receive a maximum weekly benefit of $1,228.53, which is based on 67% of the state average weekly wage. You can buy these policies through private carriers or the state fund.
A common mistake among Buffalo contractors is misclassifying workers as 1099 subcontractors. If the "sub" lacks their own coverage, your carrier will add their payroll at audit, and the resulting bill can be far higher than you expected.
Commercial Auto and Cyber Liability Essentials
New York is a no-fault state. Every commercial vehicle needs liability coverage, Personal Injury Protection (PIP), and uninsured motorist coverage at state minimums. For businesses, those minimums are rarely enough. A single serious crash on the I-190 can produce claims that blow past basic limits within months.
If your employees drive their own cars on company errands, such as a bank run or a client visit, you need hired and non-owned auto (HNOA) coverage. It's inexpensive, and it closes a gap that many small offices don't know they have.
Cyber liability has moved from optional to expected. Buffalo's healthcare, accounting, and legal firms handle sensitive data that triggers breach notification duties under New York's SHIELD Act. Cyber policies typically cover forensic investigation, customer notification, ransomware response, and regulatory defense. For accountants, a single phishing email that leads to a client tax data breach can generate costs well beyond what most small firms keep in reserve.
Why Personal Auto Policies Fall Short for Business
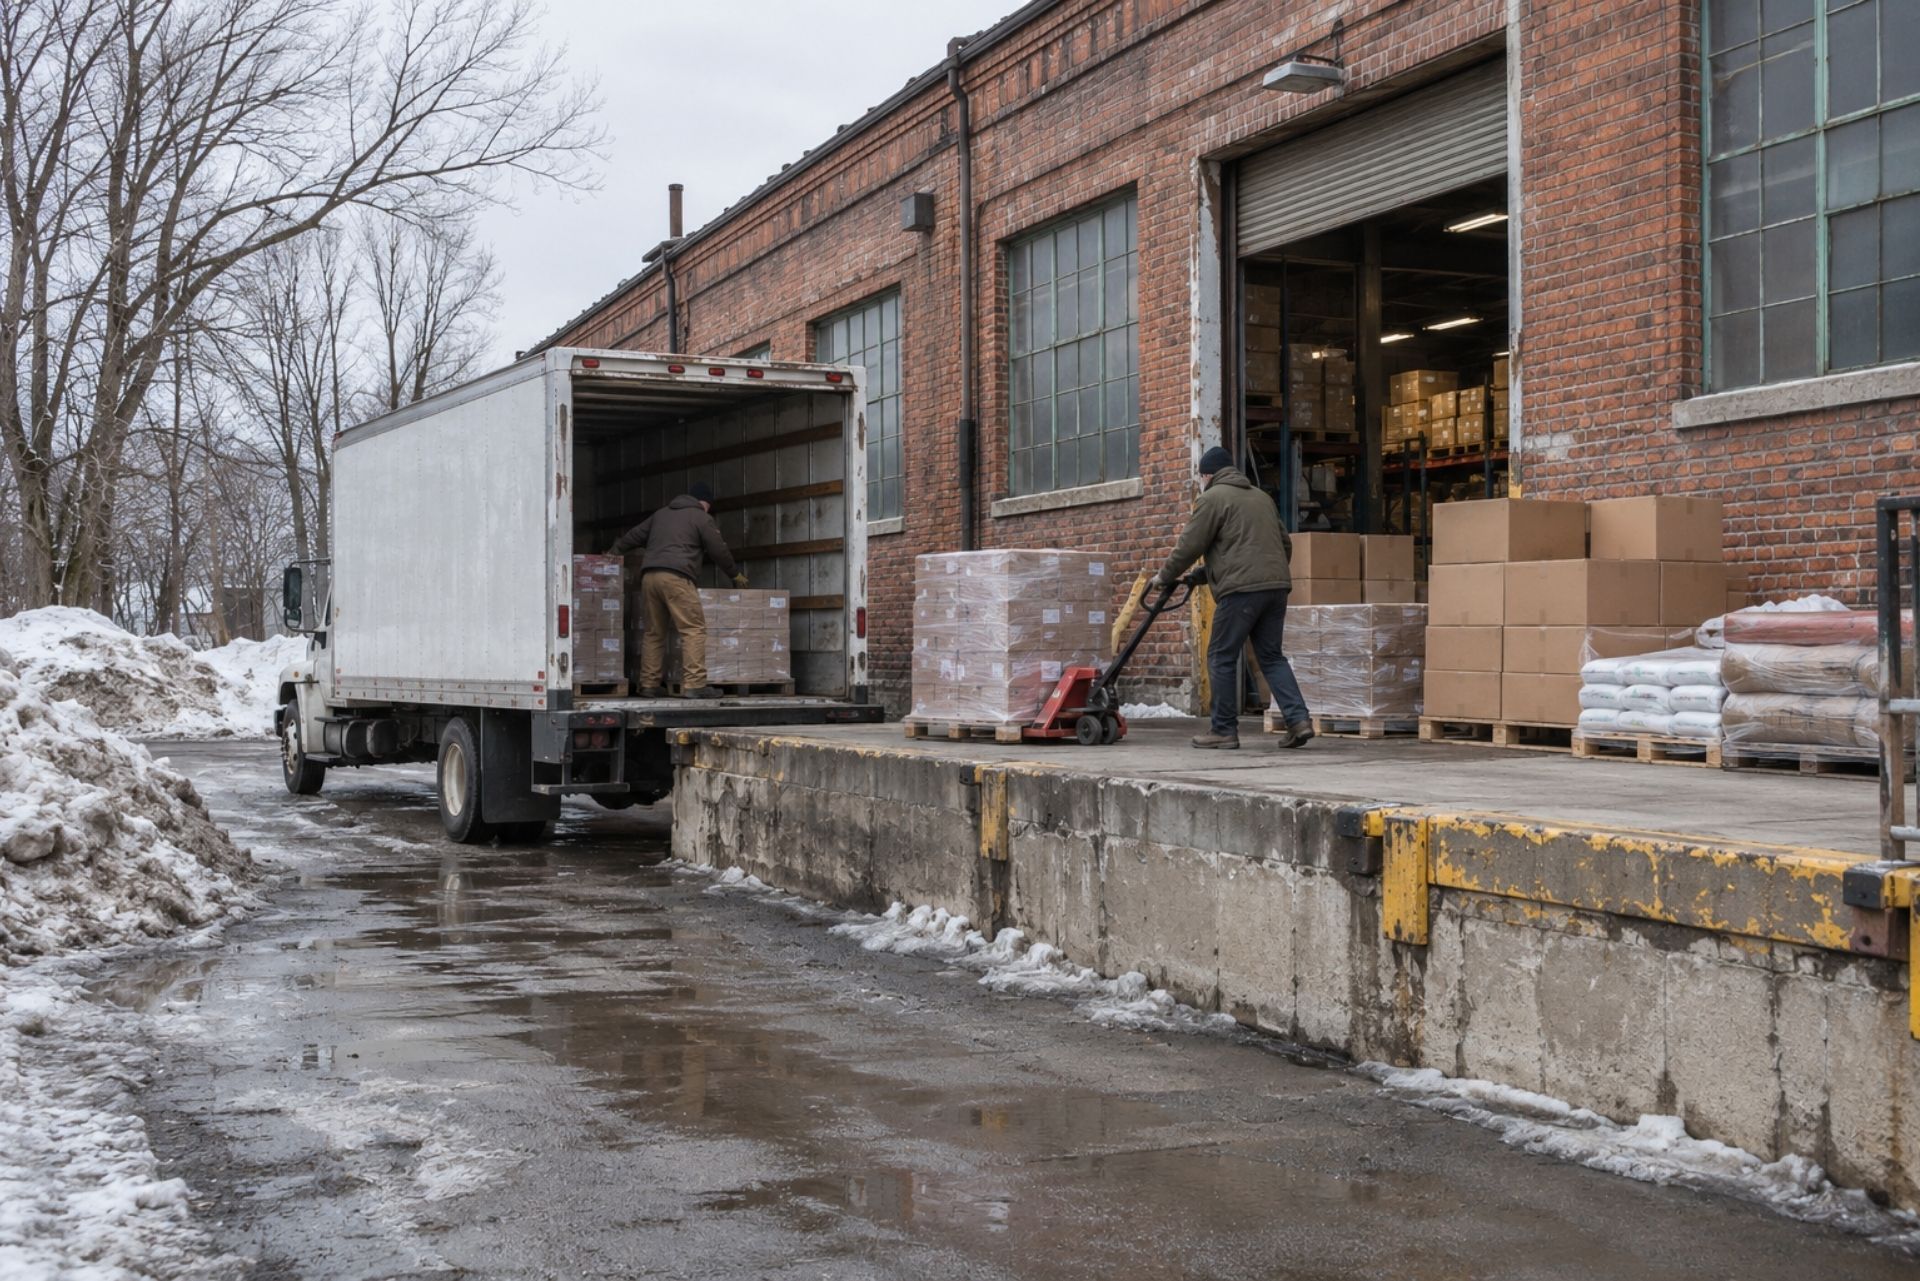
Personal auto policies usually exclude vehicles used mainly for business, especially for deliveries, hauling tools, or transporting clients. If you're a plumber in Cheektowaga driving a pickup loaded with equipment and you cause an accident on a job, your personal carrier may deny the claim outright.
Even if the claim gets paid, the personal limits are often too low and the insurer may cancel your policy afterward. A commercial auto policy also lets you list multiple drivers, insure ladders and racks, and carry higher liability limits that clients and general contractors demand.
Limits matter as much as coverage types. Here's how basic and stronger setups compare for a typical small Buffalo business.
| Coverage | Basic Setup | Stronger Setup | Why It Matters |
|---|---|---|---|
| General Liability | $1M per occurrence | $1M / $2M aggregate + umbrella | Meets most lease and contract terms |
| Property | Actual cash value | Replacement cost + business income | ACV subtracts depreciation at claim time |
| Commercial Auto | State minimums | $1M combined single limit | Minimums rarely cover serious injuries |
| Workers' Comp | Statutory coverage | Statutory + higher employer's liability | Protects against employee lawsuits |
| Cyber | None or a small endorsement | Standalone policy | Endorsements often cap breach costs low |
| Umbrella | None | $1M to $5M | Sits above GL, auto, and employer's liability |
An umbrella policy is one of the best values in commercial insurance. It extends your liability protection across several policies for a relatively small added premium. Contractors bidding on municipal or university projects in Erie County often need one just to qualify.
Estimating Your Business Insurance Costs in Buffalo
No honest broker can quote your premium without your details. That said, you can understand what drives the price and how to keep it down.
The biggest cost factors include:
- Industry and class code. A roofing contractor pays far more for GL and workers' comp than a graphic designer.
- Payroll and revenue. Workers' comp and many GL policies are rated on these figures, then adjusted at audit.
- Claims history. A clean five-year loss run can earn better pricing.
- Building age and construction. Masonry buildings with updated systems generally rate better than older frame structures.
- Vehicles and drivers. Driver records and vehicle types heavily affect commercial auto.
Upstate pricing helps. The roughly $540 median for small service GL in this region compares favorably with about $890 in NYC. Pairing that with the October 2026 workers' comp rate cut means many Buffalo employers should see lower renewals this cycle.
To control costs, bundle GL and property into a BOP when you're eligible, raise deductibles if you have cash reserves, and set up a written safety program. Most importantly, report payroll accurately. Underestimating it to lower your deposit premium just moves the cost to an audit bill later, often at an inconvenient time.
Common Questions About Buffalo Business Insurance
Do I need workers' comp if I only have one part-time employee? Yes. New York requires workers' comp, disability, and PFL coverage for nearly all employers, including those with a single part-time worker.
Is general liability required by law in New York? No state law mandates it for most businesses. Landlords, clients, and licensing bodies almost always require it, though.
Does my property policy cover snow damage to my roof? Usually, yes, if the roof collapses from snow weight. Check whether your policy pays replacement cost or actual cash value on older roofs.
Can I use my personal car insurance for my small business? Only for very occasional business errands. Regular business use, deliveries, or carrying equipment calls for a commercial auto policy.
How much does cyber insurance cost for a small Buffalo office? It depends on your revenue, the type of data you hold, and your security controls. Multi-factor authentication and offline backups usually improve pricing.
When will I see the workers' comp rate decrease? The decrease applies to policies renewing on or after October 1, 2026. Your actual change depends on your class code and loss history.
The Bottom Line for Local Business Owners
Buffalo gives you a pricing advantage over downstate businesses, but Western New York weather and New York's strict employer mandates leave little room for shortcuts. Start with what the law requires: workers' comp, disability, and PFL. Then add GL and property coverage that matches your lease and building, commercial auto for any vehicle that works for the business, and cyber coverage if you store client data.
Review your policies every year, especially this cycle, since the 2026 workers' comp rate drop could free up budget for an umbrella or a standalone cyber policy. Before you renew, ask your broker three questions. Is my roof covered at replacement cost? Is flood excluded? Do I have hired and non-owned auto coverage? The answers will tell you more about your protection than the premium total ever will.
ABOUT THE AUTHOR:
BARNABY JOYCE
Barnaby Joyce is the President of Joyce Insurance Agency. He and the Joyce team help New York families and businesses compare their options and find coverage that fits their needs.
Contact Us
Comprehensive Coverage for Businesses of All Sizes
Protecting Your Business, Securing Your Future
General Liability Insurance
Protection against lawsuits and third-party claims.
Workers Comp Insurance
Required protection for employees in case of injury or illness.
Commercial Property Insurance
Coverage for buildings, equipment, and business assets.
Commercial Auto Insurance
Coverage for company vehicles and fleet operations.
Commercial Umbrella Insurance
Protection against errors, omissions, and negligence claims.
Business Owner's Policy
A bundled policy combining essential business coverages.
Personalized Insurance for Every Stage of Life
Protect What Matters Most with Comprehensive Coverage
Jewelry Insurance
Specialized protection for valuable items like engagement rings, watches, and heirlooms.
Pet Insurance
Financial protection for veterinary care and unexpected pet health expenses.
Specialized Insurance for Your Business Needs
Serving the Industries That Drive
New York & New Jersey
What Our Clients Say
Trusted by Businesses & Families Across New York & New Jersey
Frequently Asked Questions
Get Answers to Your Insurance Questions
We understand that insurance can be complex. Here are answers to some of the most common questions our clients ask. If you need more information, our team is always here to help.
- Still have questions?
How do I know what coverage I need?
Choosing the right insurance starts with understanding your risks. For personal insurance, consider factors like your home’s value, your vehicle, and your financial responsibilities. Homeowners may need additional protection for floods or valuable belongings, while drivers should evaluate coverage limits based on their assets.
For businesses, the right coverage depends on the industry, number of employees, and liability risks. General liability is essential for most businesses, but some may need property, workers’ compensation, or business owner’s policies. Our team can assess your needs and guide you to the best options.
What factors affect my insurance rate?
Insurance rates are influenced by multiple factors. For auto policies, your driving history, vehicle type, and location play a major role. Home insurance costs depend on your home’s value, construction type, and potential risks like flooding or fire hazards.
For business insurance, rates vary based on the industry, size, claims history, and coverage limits. High-risk industries may require specialized policies, while businesses with strong safety measures and claims-free histories can qualify for better rates. Our agents help find discounts and cost-saving opportunities.
Why should I work with an independent insurance agency?
Unlike captive agents who represent a single insurance company, independent agencies like Joyce Insurance Agency work with multiple carriers to find the best coverage for your needs. This means you get more choices, competitive rates, and a policy that truly fits your situation.
We take the time to understand your needs, compare options, and provide expert advice. Whether you're insuring your home, car, or business, our priority is finding you the best protection at a great value.
How quickly can I get insured?
The time it takes to secure a policy depends on the type of insurance. Auto and home policies can often be issued the same day, while business insurance may take longer, especially for specialized coverage. Workers’ compensation and commercial policies may require underwriting approval, which can extend the timeline.
We prioritize efficiency and make the process as smooth as possible. Once we understand your needs, we work quickly to get you insured with minimal hassle.
What should I do if I need to file a claim?
If you need to file a claim, contact us as soon as possible. We’ll guide you through the process and ensure you have everything needed to submit your claim correctly. Gathering necessary documentation, such as photos, receipts, or witness statements, can help speed up the process.
We work directly with your insurance provider to streamline communication and advocate on your behalf. Our goal is to make sure your claim is handled quickly and fairly so you can recover without unnecessary stress.
How can I lower my insurance costs?
There are several ways to reduce insurance premiums without sacrificing coverage. For auto insurance, maintaining a clean driving record, bundling policies, and increasing deductibles can help lower costs. Homeowners can save by installing security systems, upgrading safety features, and bundling home and auto policies.
For business owners, implementing risk management strategies, maintaining a claims-free history, and working with an independent agent to find competitive rates can lead to cost savings. Our team helps you explore discounts and options to ensure you’re getting the best value.
Contact Us
Phone
Location