
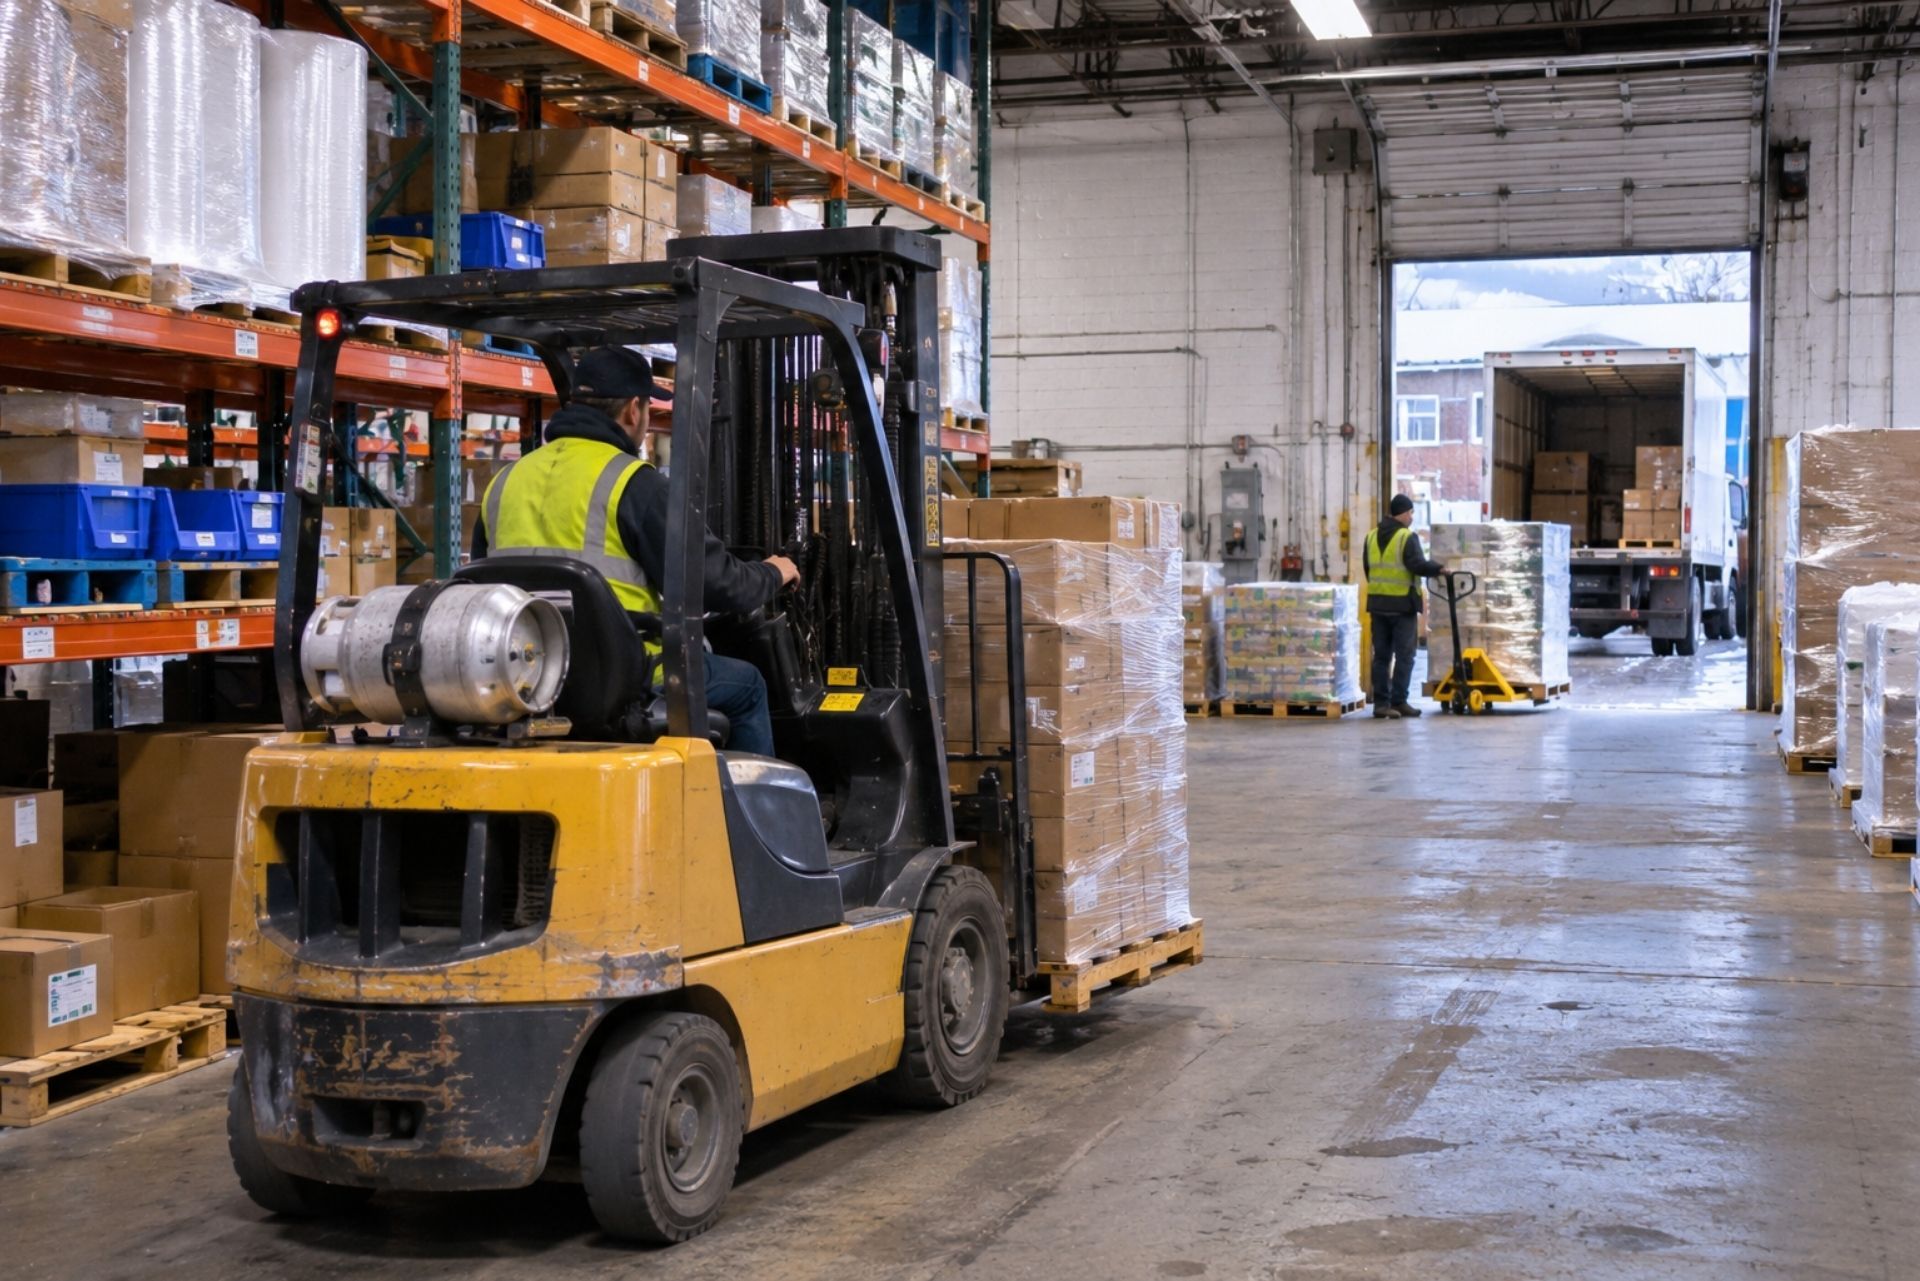
A delivery van backs into a customer's car on East Avenue. A week later, a warehouse employee in Gates tears a rotator cuff lifting a pallet. Then a phishing email locks up your client files. That's three claims in one month, and without the right policies, any one of them can drain a small business. This guide to business insurance in Rochester, NY covers general liability, property, commercial auto, workers' compensation, cyber, and costs, with a focus on what you actually need and what local owners commonly get wrong.
Rochester's market has its own quirks. Lake-effect snow, older commercial buildings, and rising liability verdicts across Monroe County all shape what you'll pay. Some lines are getting cheaper in 2026 while others keep climbing, so a policy you bought three years ago may no longer fit your risks or your budget.
Essential Insurance Coverages for Rochester Small Businesses
Most Rochester businesses need a core package of four or five policies. The exact mix depends on whether you have employees, vehicles, a physical location, or customer data. A home-based bookkeeper in Pittsford and a roofing contractor in Greece face completely different exposures, but both need a foundation.
General Liability and Property Protection
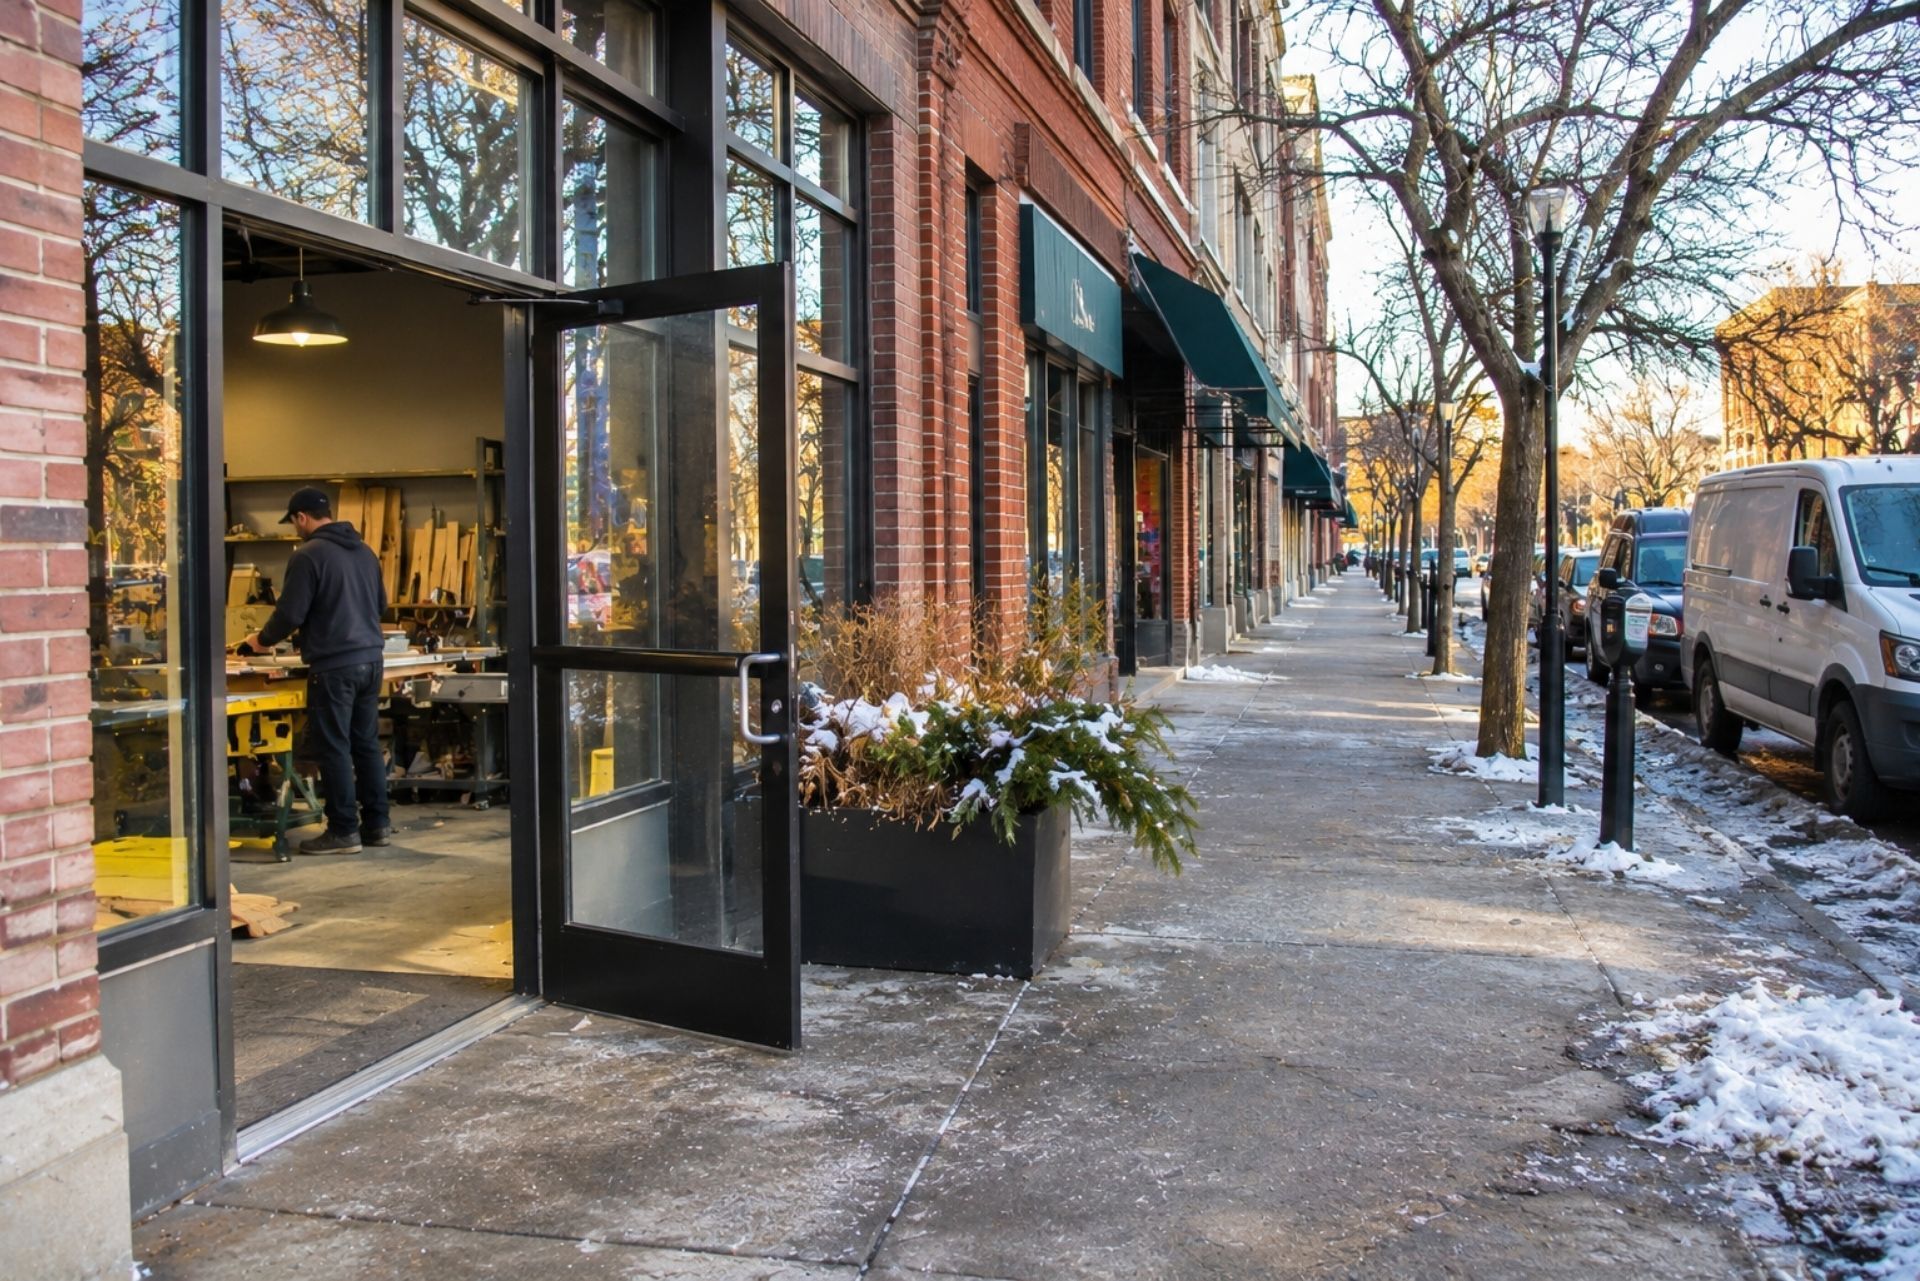
General liability covers third-party bodily injury, property damage, and advertising injury. The classic Rochester claim is a slip-and-fall on an icy entrance in February. If a customer breaks a wrist outside your Monroe Avenue shop, GL pays for medical bills and legal defense.
Property insurance protects your building, equipment, inventory, and furniture. Here's the catch: standard policies often exclude flood and sewer backup, two real risks in older Rochester neighborhoods with aging drainage. For a restaurant, a backed-up sewer line can mean over $40,000 in lost stock and cleanup with no coverage at all. Ask for a sewer backup endorsement and business interruption coverage.
Many small businesses bundle both into a Business Owner's Policy (BOP), which usually costs less than buying them separately.
Commercial Auto and Workers' Compensation Requirements
Your personal auto policy almost certainly won't cover a vehicle used for business. If your HVAC tech drives to job sites in a company van, you need commercial auto. New York also follows a no-fault system, so policies must include Personal Injury Protection (PIP) along with liability coverage.
Workers' compensation is mandatory for nearly every New York employer with even one employee, including part-time staff and many family members. It covers medical care and lost wages for work-related injuries. For an injured worker today, the
maximum weekly benefit is $1,281.50 for July 1, 2026, through June 30, 2027.
New York State Mandates vs. Optional Protections
New York requires three things from most employers: workers' compensation, disability benefits (DBL), and Paid Family Leave. Businesses with registered vehicles also need commercial auto meeting state minimums. Everything else, including general liability, property, and cyber, is technically optional.
Technically optional doesn't mean practically optional. Most commercial leases require GL with specific limits, and lenders demand property coverage on financed buildings. General contractors working in Rochester routinely require subcontractors to carry GL and name them as additional insureds before stepping onto a site.
PFL is funded through employee payroll deductions. For 2026, the employee contribution rate is 0.432% of gross wages, capped at $411.91 per year. You're responsible for collecting it correctly.
Comparison: Basic Compliance vs. Comprehensive Coverage
| Coverage | Basic Compliance | Comprehensive Approach |
|---|---|---|
| Workers' Comp | Required, state minimums | Required, plus safety programs for credits |
| Disability & PFL | Required | Required |
| Commercial Auto | State minimum limits | $1M liability, higher SUM limits |
| General Liability | Not required by law | $1M/$2M limits, often lease-required |
| Property | Not required | Replacement cost, sewer backup, BI |
| Cyber | Not required | First- and third-party coverage |
| Umbrella | Not required | $1M to $5M excess |
A business that only meets the legal minimums is one serious lawsuit away from closing.
Addressing Modern Risks: Cyber Liability and Data Security
Rochester has a strong concentration of healthcare practices, accounting firms, and tech companies, all holding sensitive data. New York's SHIELD Act requires businesses that store residents' private information to maintain reasonable security safeguards and notify affected people after a breach. Notification costs, forensic investigations, and legal fees add up quickly.
Cyber coverage for accountants is a good example. A ransomware attack during tax season can freeze client files for days. A solid cyber policy pays for forensic experts, client notification, credit monitoring, business interruption, and defense if clients sue.
Your general liability policy almost certainly excludes cyber events. Here's a quick Don'ts checklist:
- Don't assume your GL or BOP covers data breaches.
- Don't skip multi-factor authentication. Many carriers now require it to bind coverage.
- Don't ignore social engineering coverage. Fraudulent wire transfer losses are often sublimited or excluded.
- Don't
forget vendor risk. A breach at your payroll provider can still expose you.
Understanding the Cost of Business Insurance in Monroe County
Rochester premiums in 2026 are moving in two directions. Workers' comp and property are easing, while liability and auto keep rising.
The good news first. New York businesses saw a 22% average decrease in workers' comp loss cost rates effective October 1, 2026, with an average projected saving of $1,779 per policy. Property is softening too, with U.S. commercial property rates dropping an average of 13% in Q2 2026, the eighth straight quarterly decline.
On the flip side, Monroe County faces double-digit premium increases in liability lines driven by social inflation, with median auto premiums up 32.3% between January 2023 and January 2026. Larger jury awards push GL and commercial auto prices higher. State auto reforms taking effect in late 2026 cap non-economic damages at $100,000 for certain at-fault drivers, and insurers must reflect those savings in filings by November 27, 2026. Watch your renewal for any adjustment.
What drives your specific price:
- Industry classification and payroll size
- Claims history over the past three to five years
- Building age, construction type, and sprinkler systems
- Driver records and vehicle types
- Coverage limits and deductibles you select
Common Questions About Rochester Business Insurance
Do I need workers' comp if I only have one part-time employee? Yes. New York requires coverage for nearly all employees, including part-timers. Penalties for going without it are steep.
Does my homeowners policy cover my home-based business? Usually not, or only minimally. Business equipment, client injuries, and inventory often need a separate policy or endorsement.
What's the difference between general liability and professional liability? GL covers physical injuries and property damage. Professional liability (E&O) covers financial losses from mistakes in your advice or services.
Can I use my personal car for business deliveries? Not safely. Most personal auto policies exclude business use, so a claim during a delivery could be denied.
Why did my premium go up when I had no claims? Rates reflect market trends, not just your history. Rising liability verdicts across Monroe County affect everyone in the pool.
How much general liability should I carry? Most Rochester businesses carry $1 million per occurrence and $2 million aggregate, since leases and contracts commonly require it.
Making the Right Choice for Your Local Business
The right policy mix starts with an honest look at your actual risks. Count your employees, list your vehicles, and identify where you store customer data. Then compare those exposures against what your current policies really cover, not what you assume they cover.
A few practical moves pay off. Review your workers' comp renewal to confirm you're getting the October 2026 rate decrease. Shop your property coverage, since a softening market gives you leverage at renewal. And with liability costs climbing, consider higher deductibles or an umbrella policy rather than cutting limits.
The most common mistake Rochester owners make is buying insurance once and never revisiting it. Businesses grow, hire, and add vehicles, but their policies stay frozen in time. Schedule an annual review with a licensed independent agent who knows the Monroe County market and can quote multiple carriers.
Good coverage won't prevent the icy sidewalk or the ransomware email. It just makes sure one bad month doesn't end everything you've built.
ABOUT THE AUTHOR:
BARNABY JOYCE
Barnaby Joyce is the President of Joyce Insurance Agency. He and the Joyce team help New York families and businesses compare their options and find coverage that fits their needs.
Contact Us
Comprehensive Coverage for Businesses of All Sizes
Protecting Your Business, Securing Your Future
General Liability Insurance
Protection against lawsuits and third-party claims.
Workers Comp Insurance
Required protection for employees in case of injury or illness.
Commercial Property Insurance
Coverage for buildings, equipment, and business assets.
Commercial Auto Insurance
Coverage for company vehicles and fleet operations.
Commercial Umbrella Insurance
Protection against errors, omissions, and negligence claims.
Business Owner's Policy
A bundled policy combining essential business coverages.
Personalized Insurance for Every Stage of Life
Protect What Matters Most with Comprehensive Coverage
Jewelry Insurance
Specialized protection for valuable items like engagement rings, watches, and heirlooms.
Pet Insurance
Financial protection for veterinary care and unexpected pet health expenses.
Specialized Insurance for Your Business Needs
Serving the Industries That Drive
New York & New Jersey
What Our Clients Say
Trusted by Businesses & Families Across New York & New Jersey
Frequently Asked Questions
Get Answers to Your Insurance Questions
We understand that insurance can be complex. Here are answers to some of the most common questions our clients ask. If you need more information, our team is always here to help.
- Still have questions?
How do I know what coverage I need?
Choosing the right insurance starts with understanding your risks. For personal insurance, consider factors like your home’s value, your vehicle, and your financial responsibilities. Homeowners may need additional protection for floods or valuable belongings, while drivers should evaluate coverage limits based on their assets.
For businesses, the right coverage depends on the industry, number of employees, and liability risks. General liability is essential for most businesses, but some may need property, workers’ compensation, or business owner’s policies. Our team can assess your needs and guide you to the best options.
What factors affect my insurance rate?
Insurance rates are influenced by multiple factors. For auto policies, your driving history, vehicle type, and location play a major role. Home insurance costs depend on your home’s value, construction type, and potential risks like flooding or fire hazards.
For business insurance, rates vary based on the industry, size, claims history, and coverage limits. High-risk industries may require specialized policies, while businesses with strong safety measures and claims-free histories can qualify for better rates. Our agents help find discounts and cost-saving opportunities.
Why should I work with an independent insurance agency?
Unlike captive agents who represent a single insurance company, independent agencies like Joyce Insurance Agency work with multiple carriers to find the best coverage for your needs. This means you get more choices, competitive rates, and a policy that truly fits your situation.
We take the time to understand your needs, compare options, and provide expert advice. Whether you're insuring your home, car, or business, our priority is finding you the best protection at a great value.
How quickly can I get insured?
The time it takes to secure a policy depends on the type of insurance. Auto and home policies can often be issued the same day, while business insurance may take longer, especially for specialized coverage. Workers’ compensation and commercial policies may require underwriting approval, which can extend the timeline.
We prioritize efficiency and make the process as smooth as possible. Once we understand your needs, we work quickly to get you insured with minimal hassle.
What should I do if I need to file a claim?
If you need to file a claim, contact us as soon as possible. We’ll guide you through the process and ensure you have everything needed to submit your claim correctly. Gathering necessary documentation, such as photos, receipts, or witness statements, can help speed up the process.
We work directly with your insurance provider to streamline communication and advocate on your behalf. Our goal is to make sure your claim is handled quickly and fairly so you can recover without unnecessary stress.
How can I lower my insurance costs?
There are several ways to reduce insurance premiums without sacrificing coverage. For auto insurance, maintaining a clean driving record, bundling policies, and increasing deductibles can help lower costs. Homeowners can save by installing security systems, upgrading safety features, and bundling home and auto policies.
For business owners, implementing risk management strategies, maintaining a claims-free history, and working with an independent agent to find competitive rates can lead to cost savings. Our team helps you explore discounts and options to ensure you’re getting the best value.
Contact Us
Phone
Location