
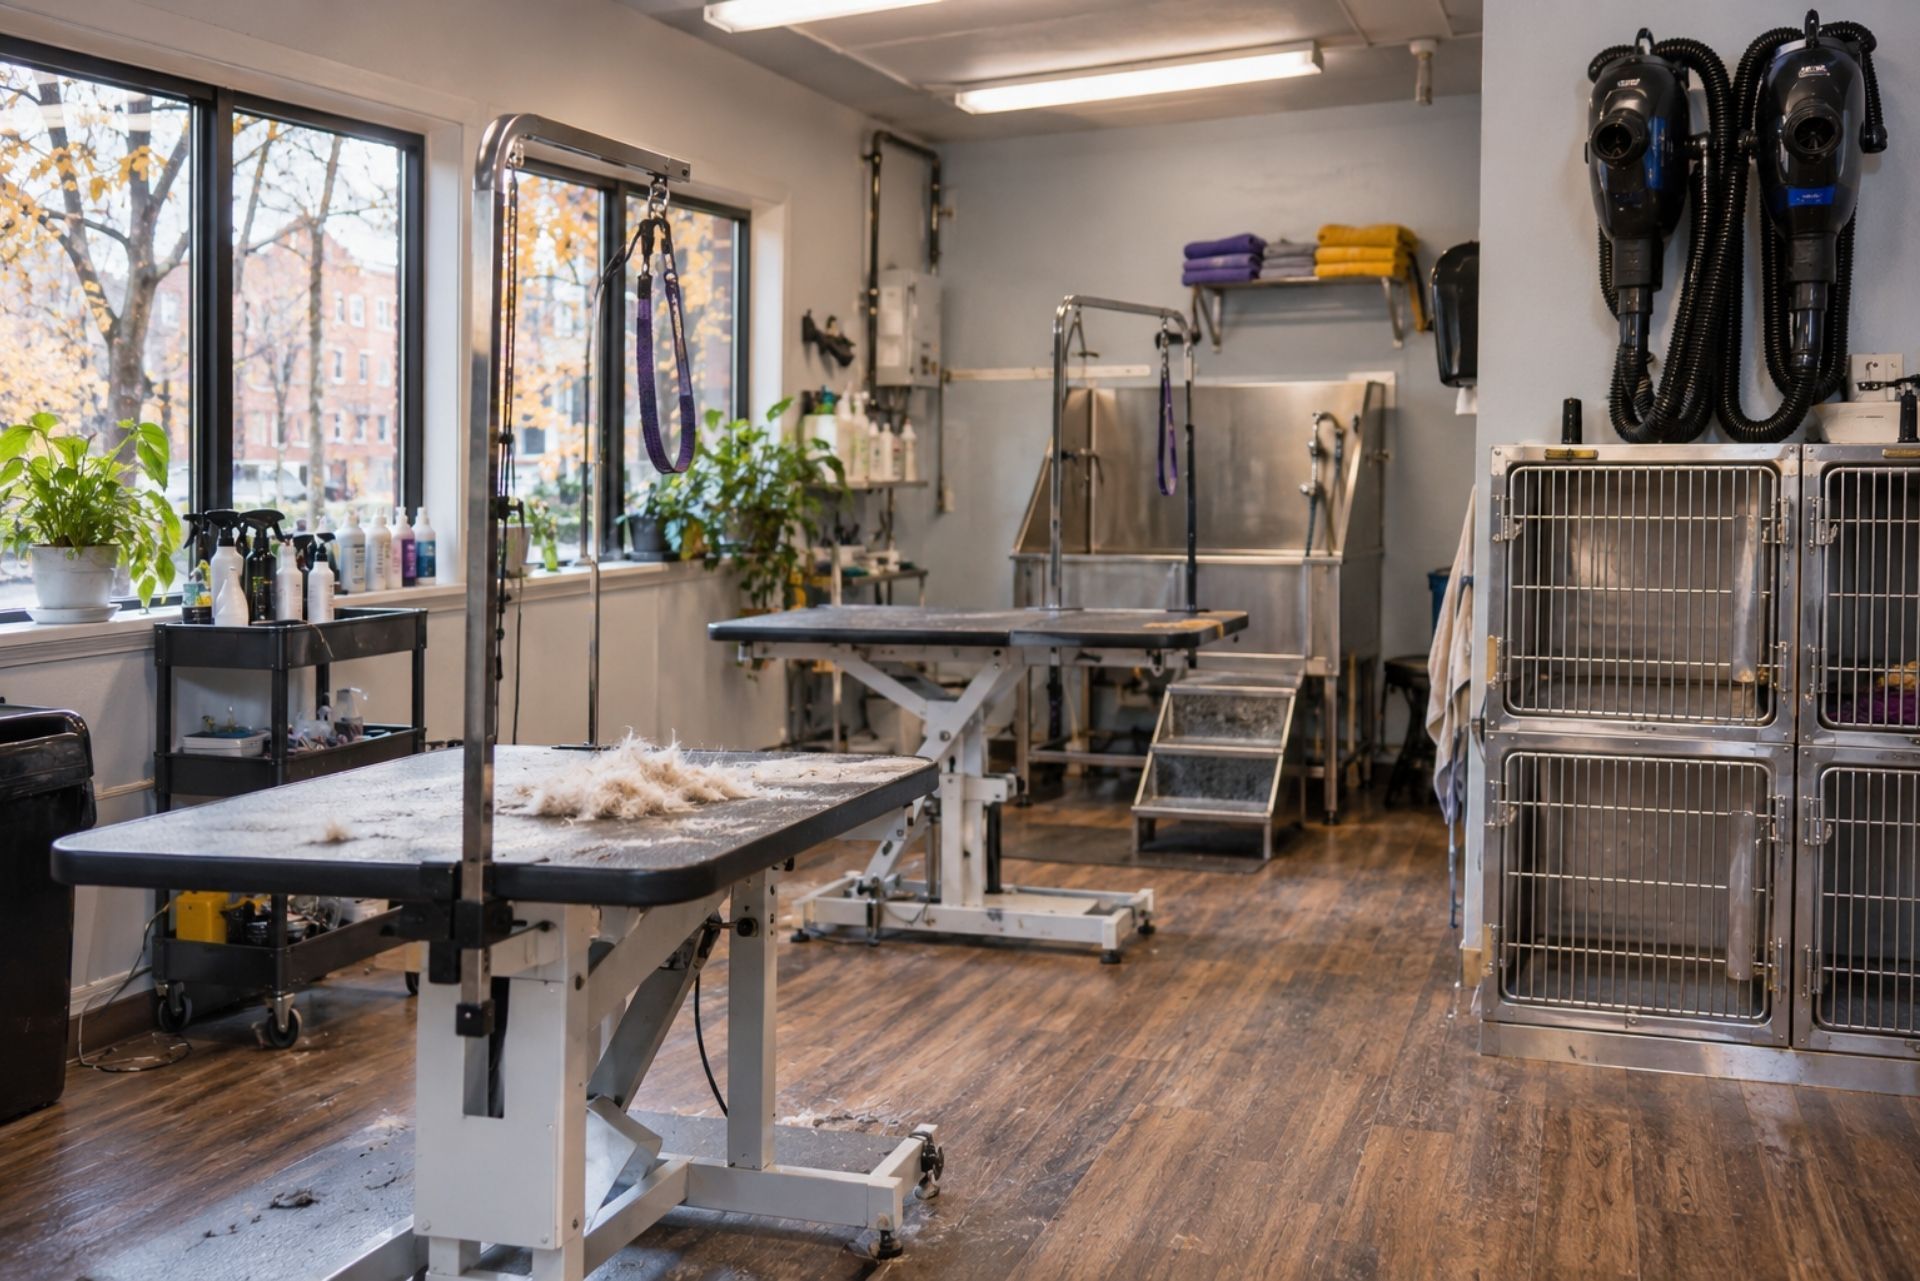
It's 9:40 on a Saturday morning in Astoria. Your forced-air dryer coughs, smells like burnt carbon, and dies with a poodle half-dried on the table and six more dogs booked before 3 p.m. By noon, the electrician says the dryer motor was the symptom. The real problem is a failing breaker in a panel that's older than your lease.
That single morning can wipe out a week of profit. This guide to
equipment breakdown insurance for
New York grooming shops covers dryers, tubs, electrical failure, lost income, and repair costs. It focuses on what owners actually run into when they file a claim, so you know what to ask before something quits on you.
Protecting Your New York Grooming Shop from Mechanical Failure
Grooming is a growing business, and it depends more on equipment than most people assume. The U.S. pet grooming market is projected to reach nearly $13 billion by the end of 2026, with annual growth of 7 to 9%. More demand means more hours on your dryers, more cycles on your hydraulic tables, and more strain on your water heater.
The money per appointment is rising too. A full groom for a medium-sized dog now averages $95, a 46% jump since 2019. That sounds like good news. It also means every canceled slot costs you more than it did a few years ago.
Here's the math that matters. Staffed salons typically run net margins of 10 to 20%. So if you lose $1,900 in bookings over a two-day shutdown, you aren't losing $1,900 in revenue. At a 15% margin, you'd need roughly $12,700 in future sales just to earn back that profit.
Equipment breakdown coverage, sometimes called boiler and machinery coverage, exists for exactly this. It pays to repair or replace equipment that fails from sudden internal causes like electrical arcing, motor burnout, or mechanical seizure. Good policies also cover the income you lose while the machine is down.
What it isn't:
- Not a maintenance plan. It won't pay to replace a dryer that simply wore out.
- Not a warranty. It doesn't care who made the equipment or when you bought it.
- Not automatic. Most standard business policies leave it out unless you add it.
Why Standard Property Insurance Isn't Enough for Groomers
Most groomers assume their business owner's policy (BOP) covers "the equipment." It does, but only against certain causes of loss. Standard commercial property forms cover external events: fire, theft, vandalism, windstorm, a car through the front window. They specifically exclude mechanical breakdown, electrical injury from artificial current, and steam boiler explosions.
That exclusion is the whole story. If your dryer gets stolen, your property policy pays. If the same dryer's motor shorts out on its own, your property policy probably pays nothing.
Mechanical Breakdown vs. Wear and Tear
This is where many claims fall apart, so it's worth understanding the difference before you need it.
Mechanical breakdown is a sudden, accidental failure. A capacitor blows, a hydraulic seal ruptures during a lift, or a power surge fries a control board. Wear and tear is gradual decline: brushes worn thin over 18 months, a pump losing pressure slowly, rust building up in a tub drain.
Equipment breakdown policies cover the first and exclude the second. In practice, adjusters look for evidence of a sudden event. A technician's report saying "motor seized due to bearing failure" reads very differently from "unit at end of service life." Ask your repair tech to describe exactly what failed and how, in writing, every time.
Don'ts that sink claims:
- Don't throw away failed parts before the adjuster sees them.
- Don't let a repair tech write "old unit" on the invoice when the failure was sudden.
- Don't skip documented maintenance. A missing service history invites a wear-and-tear denial.
The Gap Between General Liability and Equipment Coverage
General liability pays when your business injures someone else or damages their property. If a dryer overheats and burns a client's dog, GL (or more precisely, animal bailee coverage) responds to the claim from the pet owner. It does not pay to fix the dryer.
That's the gap. One failure can trigger two separate losses: the injured pet and the broken machine. Owners who carry GL and a basic BOP often discover they're covered for the lawsuit but stuck paying for the equipment and the downtime themselves.
Critical Grooming Assets Covered by Equipment Breakdown Policies
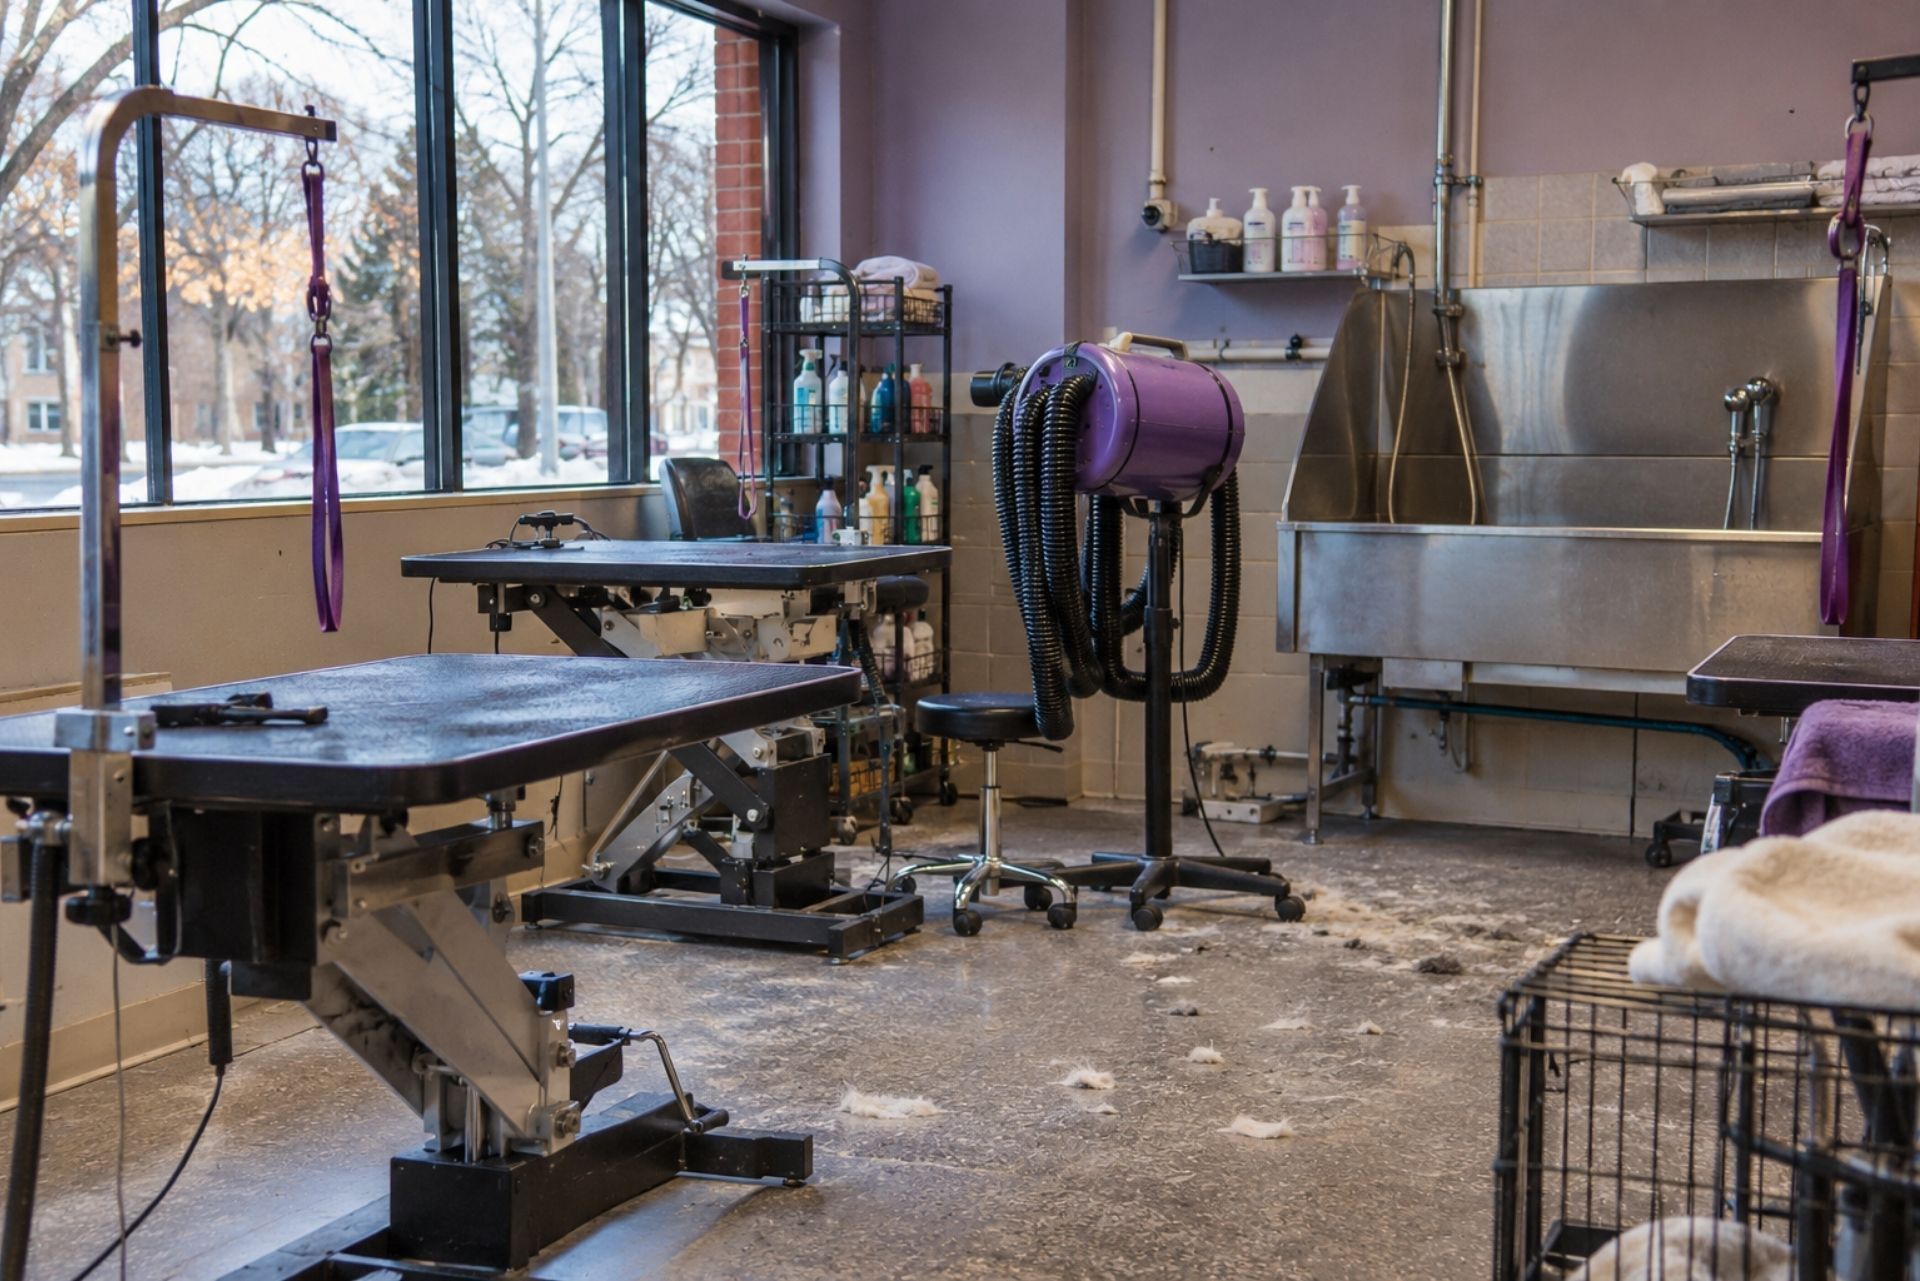
Almost everything in your shop that plugs in, heats up, pumps, or moves under power counts as covered equipment under a standard breakdown endorsement. Here's how that applies to the gear groomers depend on most.
High-Velocity Dryers and Specialized HVAC Systems
Professional dryers like dual-motor K-9 III style units are serious investments in 2026. When they fail, routine work such as motor or carbon brush replacement typically starts at $30 to $50 plus parts. That part is cheap. The expensive scenario is a motor burnout that takes out the housing or wiring, or a cage dryer failing during a session.
Your HVAC system matters just as much and gets less attention. Groomers run hot: dryers, hot water, and dogs in a tight space. If your rooftop unit or ductless system dies in July, you may have to close for animal safety reasons alone. Breakdown coverage generally treats HVAC compressors and air handlers as covered equipment, but check whether your lease makes the landlord or you responsible for the unit. If it's the landlord's equipment, their policy pays for the repair, and your lost income is still your problem.
Hydraulic Tubs and Electric Grooming Tables
Hydraulic and electric lift tables carry repeated loads all day. Typical sudden failures include:
- Ruptured hydraulic lines or seals causing a table to drop or stop lifting
- Burned-out lift motors on electric tables
- Failed control switches or foot pedals
- Tub pump and recirculation failures on bathing systems
Tubs bring plumbing exposure along with them. Minor plumbing repairs for faucets or fixtures average $175 to $340 in 2026, while burst pipe repairs average around $1,600. Here's a nuance: a breakdown policy may cover a failed tub pump or water heater, but water damage to your floors and walls usually falls under property coverage instead. You want both lined up so nothing slips between them.
Electrical Panels and Power Surge Vulnerabilities
This is the one that surprises owners. A grooming shop pulls heavy, continuous loads: multiple dryers, clippers charging, washers, water heaters, and HVAC all running at once. Many storefronts in Queens, Brooklyn, and older upstate downtowns weren't wired for that.
Electrical injury is a core breakdown peril. That includes arcing in a panel, a transformer failure, or a surge that damages several devices at once. A single surge can kill a dryer's control board, your POS terminal, and a washer in one hit. Confirm that your policy covers surge damage originating both inside and outside your building, since some forms treat utility-side surges differently.
Comparison: Basic Property vs. Equipment Breakdown Coverage
The table below shows how each policy typically responds to the failures groomers actually report. Exact wording varies by carrier, so treat this as a starting point for a conversation with your agent, not a guarantee.
| Scenario | Basic Property / BOP | Equipment Breakdown Endorsement |
|---|---|---|
| Dryer motor burns out on its own | Usually excluded | Covered (repair or replace) |
| Dryer stolen in a break-in | Covered | Not applicable |
| Power surge fries control boards | Often excluded | Covered |
| Hydraulic table seal ruptures | Excluded | Covered |
| Water heater fails suddenly | Excluded | Covered |
| Fire spreads from failed equipment | Fire damage covered | Failed unit itself covered |
| Lost income from equipment downtime | Generally no | Covered if business income is included |
| Spoiled medicated shampoo or supplies | No | Sometimes, via spoilage sublimit |
| Equipment simply worn out | No | No |
| Rush shipping for replacement parts | No | Covered under expediting expenses |
The last row is worth a look. Neither policy covers gradual wear. That's why your maintenance records matter as much as your coverage limits.
Managing Lost Income and Business Interruption
Repairing a dryer is a few hundred dollars. Losing three days of appointments is the real loss. Breakdown policies can include business income coverage, but how it's written determines whether it actually helps.
Three terms to check on your declarations page:
- Waiting period (time deductible). Many policies don't pay lost income until the equipment has been down for 12, 24, or 72 hours. For a salon booked tight on weekends, a 72-hour wait can mean you collect nothing for a typical short outage. Ask about shortening it.
- Extra expense. This pays for costs you take on to stay open, like renting a portable dryer, sending dogs to a partner salon, or paying staff overtime to catch up on rebooked appointments.
- Utility service interruption. If a Con Edison or National Grid failure cuts your power, that's a separate coverage. Your own panel failing is a breakdown claim. The utility's transformer failing is not, unless you've added utility service coverage.
Here's what that means for you: document everything. Keep your booking software exports, canceled appointment lists, and prior-year revenue for the same weeks. Adjusters calculate lost income based on what you can prove you would have earned. A shop with clean records from its scheduling platform settles faster and more completely than one working from memory.
One common mistake is canceling clients without logging why. Note "equipment failure" in your system for every canceled appointment. It builds your claim file automatically.
The Financial Impact of Repairs and Expediting Expenses
Professional grooming equipment often isn't sitting on a shelf in a local store. Specialized dryer motors, table hydraulics, and tub pumps may ship from a single distributor, and standard ground shipping can take a week or more. That's a week of reduced capacity.
Expediting expense coverage pays the extra cost of getting you running faster. That includes overnight freight, after-hours technician rates, and temporary repairs to keep a unit working until the permanent part arrives. Sublimits on this coverage are often modest, so check yours.
Then there's the repair-or-replace question. Good breakdown forms pay replacement cost, and some include an upgrade provision. If the dryer that died is obsolete, the policy can pay toward a more energy-efficient model instead of hunting down a used equivalent. Older or cheaper forms pay actual cash value, which subtracts depreciation. On a five-year-old dryer, that gap can leave you covering most of the replacement yourself.
Ask your agent directly:
- Is the valuation replacement cost or actual cash value?
- What's the expediting expense sublimit?
- Does the policy include "green upgrade" or code-upgrade coverage?
- Is there a separate deductible for breakdown claims, and is it per occurrence or per item?
That last question matters. A per-item deductible on a surge that kills four devices can quietly quadruple your out-of-pocket cost.
Unique Risks for New York City and State Grooming Shops
New York adds pressure that groomers in newer suburban strip centers don't face. In NYC, many grooming shops sit in pre-war mixed-use buildings with aging electrical service and shared risers. Heavy dryer loads on old wiring increase the odds of panel arcing and breaker failure. The July 2019 Manhattan blackout reminded businesses how fast grid problems spread during summer peak demand, and heat waves still strain local networks every year.
Leases are another trap. Commercial leases in the city often push repair responsibility for HVAC, water heaters, and even electrical systems onto the tenant. If your lease says you maintain the rooftop unit, you need breakdown coverage that includes it. Read the repair clause before you assume the landlord pays.
Upstate shops face a different set of risks. In Buffalo, Rochester, Syracuse, and the North Country, winter brings frozen supply lines, overworked boilers, and ice-storm power outages that cause surges when service comes back. A boiler or water heater failure in January can close a salon until it's fixed, since bathing dogs without hot water isn't an option.
Mobile groomers across the state should know that equipment mounted in a van, such as generators, water heaters, and onboard dryers, often isn't covered by commercial auto. That gear needs inland marine or a breakdown endorsement written specifically for mobile equipment.
Frequently Asked Questions About Grooming Equipment Insurance
Does my business owner's policy already cover broken grooming dryers? Usually not if the dryer failed on its own. Most BOPs exclude mechanical and electrical breakdown unless you've added an equipment breakdown endorsement.
How much does equipment breakdown coverage cost for a grooming salon? It's typically an add-on to your BOP, and pricing depends on your equipment values, location, and claims history. Ask your agent to quote it as a separate line so you can see the actual cost.
Will insurance pay if my dryer just got old and stopped working? No. Gradual wear and tear is excluded. Coverage applies to sudden, accidental failures like motor burnout, electrical arcing, or a ruptured seal.
Is a power outage from the utility company covered? Not under standard breakdown coverage. You need utility service interruption coverage for outages that start off your premises.
Do I need this if I rent my space and the landlord owns the HVAC? Probably yes. Even if the landlord pays to fix their unit, your lost income during the outage isn't covered by their policy.
What should I do right after a piece of equipment fails? Unplug it, photograph it, keep the failed parts, and call your agent before authorizing major repairs. Log every canceled appointment as equipment-related.
What This Means for Your Business
Your dryers, tables, tubs, and electrical panel are what keep revenue coming in. Standard property coverage protects them from outside threats like fire and theft, but it usually ignores the far more common problem: equipment failing on its own. With rising per-groom prices and thin net margins, a single breakdown with a long waiting period can erase a month of profit.
The best breakdown protection for a New York grooming shop pairs replacement-cost repairs with business income, a short waiting period, expediting expense, and utility interruption coverage. Then it's backed by maintenance records that prove a failure was sudden, not gradual.
Your next step is simple. Pull your current policy tonight, search for "mechanical breakdown" in the exclusions, and check your lease's repair clause. If either one leaves you exposed, call your agent this week, before your busiest dryer decides the matter for you.
ABOUT THE AUTHOR:
BARNABY JOYCE
Barnaby Joyce is the President of Joyce Insurance Agency. He and the Joyce team help New York families and businesses compare their options and find coverage that fits their needs.
Contact Us
Comprehensive Coverage for Businesses of All Sizes
Protecting Your Business, Securing Your Future
General Liability Insurance
Protection against lawsuits and third-party claims.
Workers Comp Insurance
Required protection for employees in case of injury or illness.
Commercial Property Insurance
Coverage for buildings, equipment, and business assets.
Commercial Auto Insurance
Coverage for company vehicles and fleet operations.
Commercial Umbrella Insurance
Protection against errors, omissions, and negligence claims.
Business Owner's Policy
A bundled policy combining essential business coverages.
Personalized Insurance for Every Stage of Life
Protect What Matters Most with Comprehensive Coverage
Jewelry Insurance
Specialized protection for valuable items like engagement rings, watches, and heirlooms.
Pet Insurance
Financial protection for veterinary care and unexpected pet health expenses.
Specialized Insurance for Your Business Needs
Serving the Industries That Drive
New York & New Jersey
What Our Clients Say
Trusted by Businesses & Families Across New York & New Jersey
Frequently Asked Questions
Get Answers to Your Insurance Questions
We understand that insurance can be complex. Here are answers to some of the most common questions our clients ask. If you need more information, our team is always here to help.
- Still have questions?
How do I know what coverage I need?
Choosing the right insurance starts with understanding your risks. For personal insurance, consider factors like your home’s value, your vehicle, and your financial responsibilities. Homeowners may need additional protection for floods or valuable belongings, while drivers should evaluate coverage limits based on their assets.
For businesses, the right coverage depends on the industry, number of employees, and liability risks. General liability is essential for most businesses, but some may need property, workers’ compensation, or business owner’s policies. Our team can assess your needs and guide you to the best options.
What factors affect my insurance rate?
Insurance rates are influenced by multiple factors. For auto policies, your driving history, vehicle type, and location play a major role. Home insurance costs depend on your home’s value, construction type, and potential risks like flooding or fire hazards.
For business insurance, rates vary based on the industry, size, claims history, and coverage limits. High-risk industries may require specialized policies, while businesses with strong safety measures and claims-free histories can qualify for better rates. Our agents help find discounts and cost-saving opportunities.
Why should I work with an independent insurance agency?
Unlike captive agents who represent a single insurance company, independent agencies like Joyce Insurance Agency work with multiple carriers to find the best coverage for your needs. This means you get more choices, competitive rates, and a policy that truly fits your situation.
We take the time to understand your needs, compare options, and provide expert advice. Whether you're insuring your home, car, or business, our priority is finding you the best protection at a great value.
How quickly can I get insured?
The time it takes to secure a policy depends on the type of insurance. Auto and home policies can often be issued the same day, while business insurance may take longer, especially for specialized coverage. Workers’ compensation and commercial policies may require underwriting approval, which can extend the timeline.
We prioritize efficiency and make the process as smooth as possible. Once we understand your needs, we work quickly to get you insured with minimal hassle.
What should I do if I need to file a claim?
If you need to file a claim, contact us as soon as possible. We’ll guide you through the process and ensure you have everything needed to submit your claim correctly. Gathering necessary documentation, such as photos, receipts, or witness statements, can help speed up the process.
We work directly with your insurance provider to streamline communication and advocate on your behalf. Our goal is to make sure your claim is handled quickly and fairly so you can recover without unnecessary stress.
How can I lower my insurance costs?
There are several ways to reduce insurance premiums without sacrificing coverage. For auto insurance, maintaining a clean driving record, bundling policies, and increasing deductibles can help lower costs. Homeowners can save by installing security systems, upgrading safety features, and bundling home and auto policies.
For business owners, implementing risk management strategies, maintaining a claims-free history, and working with an independent agent to find competitive rates can lead to cost savings. Our team helps you explore discounts and options to ensure you’re getting the best value.
Contact Us
Phone
Location