
A burst pipe in a prewar building on Park Avenue can cost you $50,000 to $100,000 before anyone even talks about restoring the original plaster moldings. Your neighbor's overflowing bathtub seeps through three floors, and suddenly the board is issuing a special assessment that dwarfs your monthly maintenance. These aren't hypothetical scenarios: they're Tuesday on the Upper East Side. [https://www.insuranceopedia.com/homeowners-insurance/best-condo-insurance-new-york]
Owning a condo or co-op in one of Manhattan's most coveted zip codes comes with a particular set of insurance challenges. Between aging infrastructure, strict board requirements, and personal property worth protecting, getting the right coverage demands more than a standard policy. This guide to
condo and co-op insurance on the Upper East Side covers everything from walls-in protection and loss assessment to liability and water damage risks specific to prewar buildings. NYC multifamily insurance premiums are
rising by 20% to 30% on average in 2026, with some buildings experiencing far steeper increases. The stakes for getting your
personal policy right have never been higher. Whether you're closing on a classic six or renewing coverage on a pied-à-terre, understanding what your
building's master policy actually covers, and where it stops, is the difference between financial security and a six-figure surprise.
Understanding Upper East Side Real Estate Insurance Requirements
Your building carries a master policy. You carry a personal policy. The gap between them is where most UES owners get burned. Every co-op and condo board on the Upper East Side sets minimum insurance requirements for shareholders and unit owners, and these requirements have tightened considerably over the past two years as building-wide claims have driven up master policy costs.
Boards aren't being difficult for the sake of it. They're protecting the building's insurability. Underwriters are scrutinizing claims history, building maintenance practices, and the presence of water leak prevention systems more aggressively than ever before.
The Difference Between Co-op and Condo Master Policies
A co-op's master policy typically covers the building's structure, common areas, and sometimes the original fixtures within individual units. You, as a shareholder, own shares in a corporation, not the physical unit itself. That distinction matters for insurance. A condo master policy, by contrast, usually covers common elements and the building exterior, but the unit owner holds title to the interior space.
The practical result: condo owners generally need more walls-in coverage than co-op shareholders, because the master policy's boundary often ends at the unfinished interior surfaces. Co-op shareholders may have slightly more overlap with the building's coverage, but "slightly more" still leaves enormous gaps after a renovation.
Standard Building Requirements for UES Residents
Most Upper East Side boards require proof of an HO-6 policy with minimum liability limits of $300,000 to $500,000, though many luxury "Class A" buildings now mandate $1 million. You'll also typically need the building and its managing agent listed as additional insureds or loss payees. [https://www.insuranceopedia.com/homeowners-insurance/best-condo-insurance-new-york]
Expect your board to require a certificate of insurance before closing, before any renovation, and at each renewal. Co-op boards operating under
new Local Law 2026/058 transparency requirements must provide email and registered mail notifications regarding application status. Don't let your coverage lapse: boards track it, and gaps can trigger fines or default notices.
Essential Coverage Types for Luxury Apartments
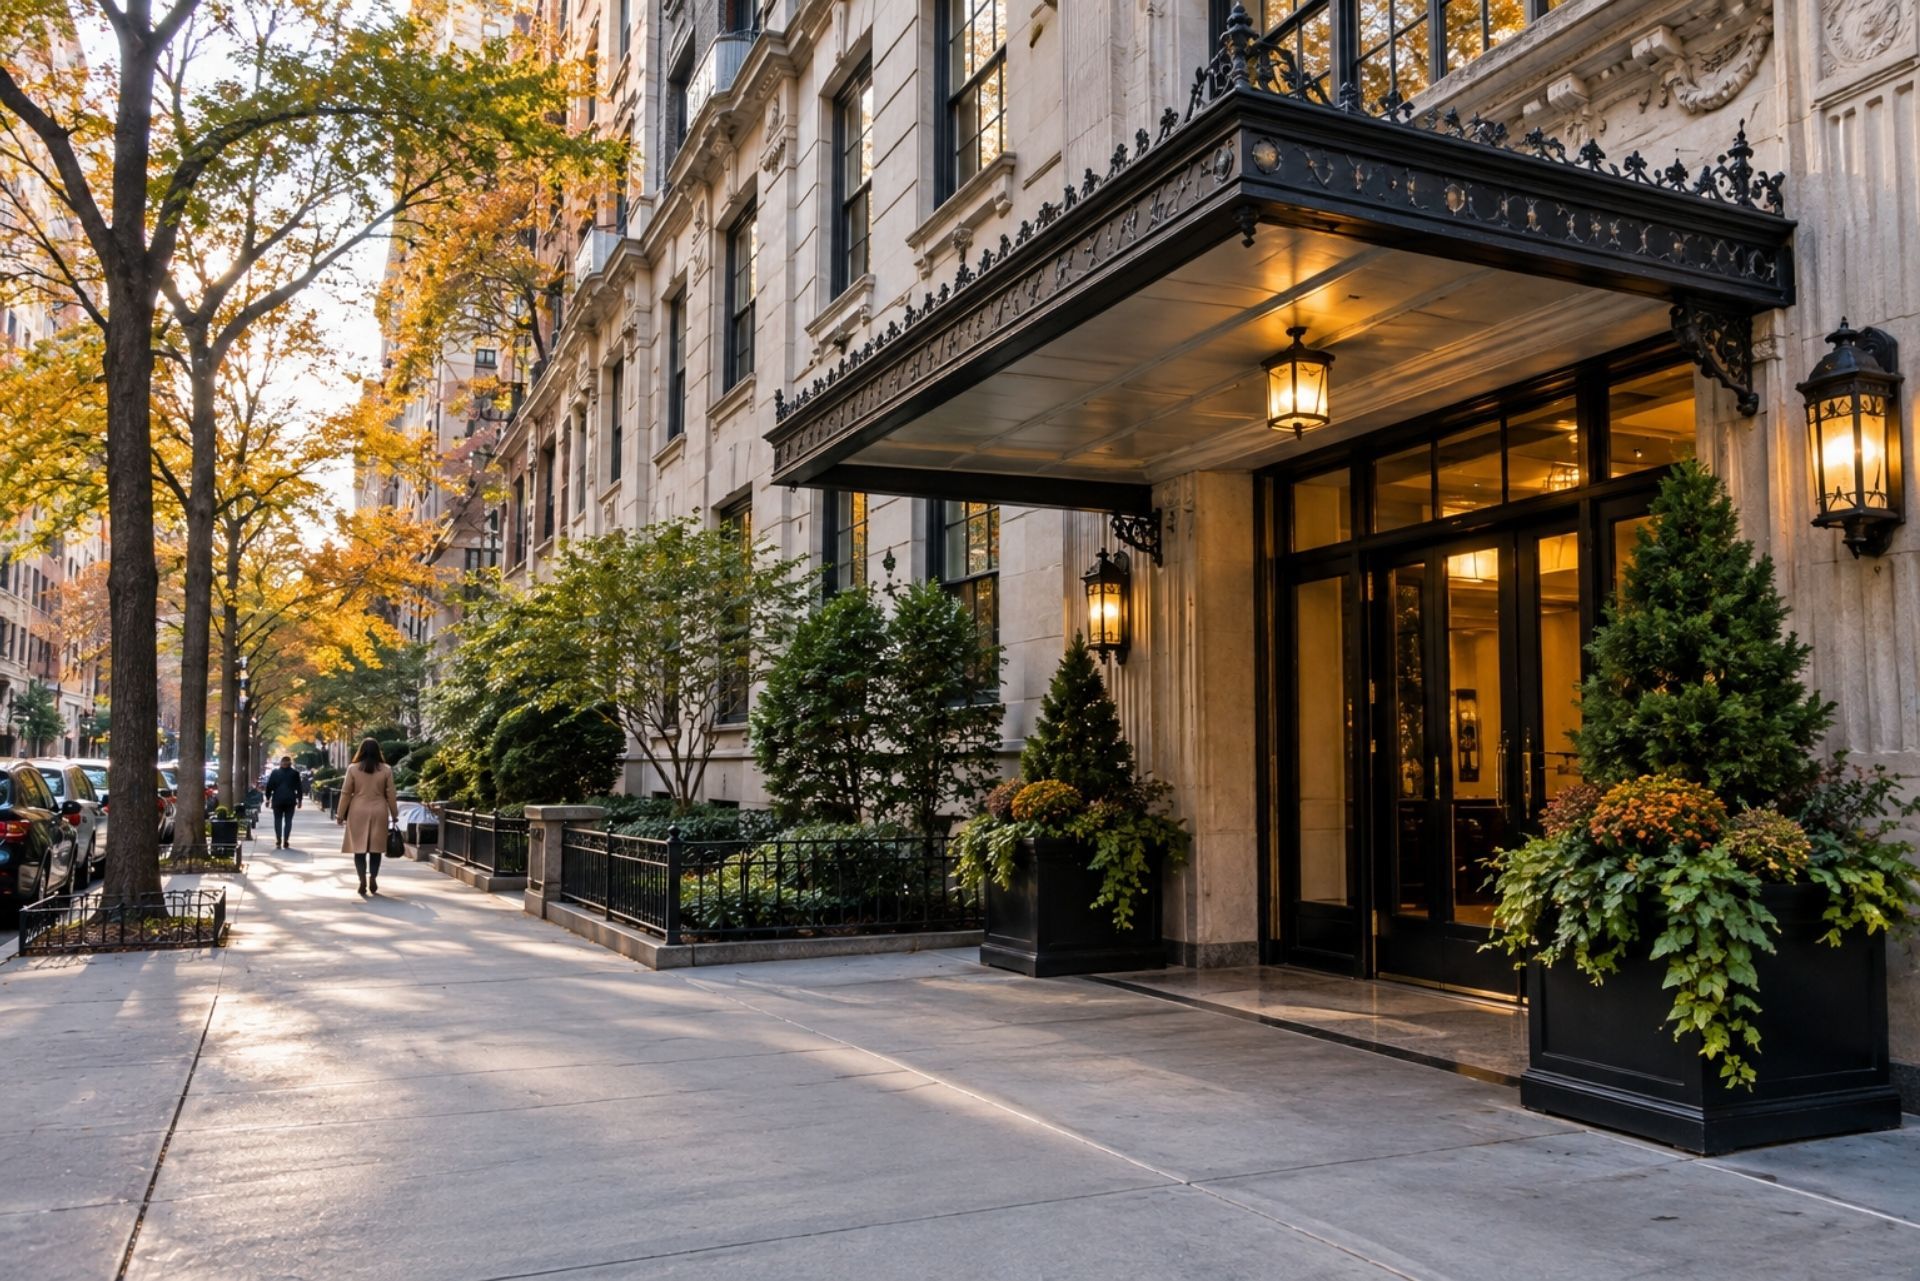
The right insurance package for an Upper East Side apartment isn't a single policy. It's a layered approach that accounts for the unique risks of high-value urban living.
Walls-In and Additions Coverage (HO-6)
Your HO-6 policy is the foundation. It covers everything from the studs inward: custom cabinetry, hardwood floors, built-in bookshelves, renovated kitchens, and bathroom finishes. If you've completed a gut renovation, your walls-in coverage needs to reflect that investment, not the generic default your insurer suggested.
One common mistake: owners assume the building's master policy covers their kitchen. After a fire, they discover it only covers the original 1928 layout, not high-end Sub-Zero and marble countertop upgrades. Get your renovation receipts and have your agent set the dwelling coverage accordingly.
Personal Liability and Loss Assessment
Personal liability coverage protects you if someone is injured inside your apartment or if you cause damage to another unit. On the Upper East Side, where a slip-and-fall lawsuit can easily exceed standard policy limits, carrying the minimum is a gamble.
Loss assessment coverage is the piece most owners overlook. Standard HO-6 policies often default to only $1,000 in loss assessment coverage, which is dangerously low. If your building's master policy carries a $250,000 deductible and the board splits that cost among 40 units, you're looking at a $6,250 assessment. Bump your loss assessment limit to at least $50,000.
High-Value Item Riders for Art and Jewelry
Standard HO-6 policies cap payouts on jewelry, fine art, and collectibles, often at $1,000 to $2,500 per category. If you own a single piece worth more than that, you need a scheduled personal property endorsement or a standalone valuable articles policy. These riders cover specific items at their appraised value with no deductible, and they typically include broader protection, such as accidental damage, that a base policy excludes. [https://www.insuranceopedia.com/homeowners-insurance/best-condo-insurance-new-york]
Comparison: Standard vs. High-Value Homeowners Policies
| Feature | Standard HO-6 | High-Value / High-Net-Worth Policy |
|---|---|---|
| Dwelling (Walls-In) | Varies by unit | Guaranteed replacement cost |
| Personal Property | Actual cash value or limited replacement | Full replacement cost, higher sub-limits |
| Liability | $300K-$500K | $1M+ with umbrella options |
| Loss Assessment | $1,000 default | $50K-$100K available |
| Art/Jewelry | $1,000-$2,500 sub-limits | Scheduled coverage at appraised value |
| Water Backup | Often excluded or $5K | Included, higher limits |
| Claims Service | Standard adjuster | Dedicated claims concierge |
For most Upper East Side owners who've renovated their apartments, a high-value policy pays for itself the first time you file a claim. The claims experience alone, with dedicated adjusters who understand prewar buildings, is worth the premium difference.
Water Damage: The Biggest Threat to Prewar UES Buildings
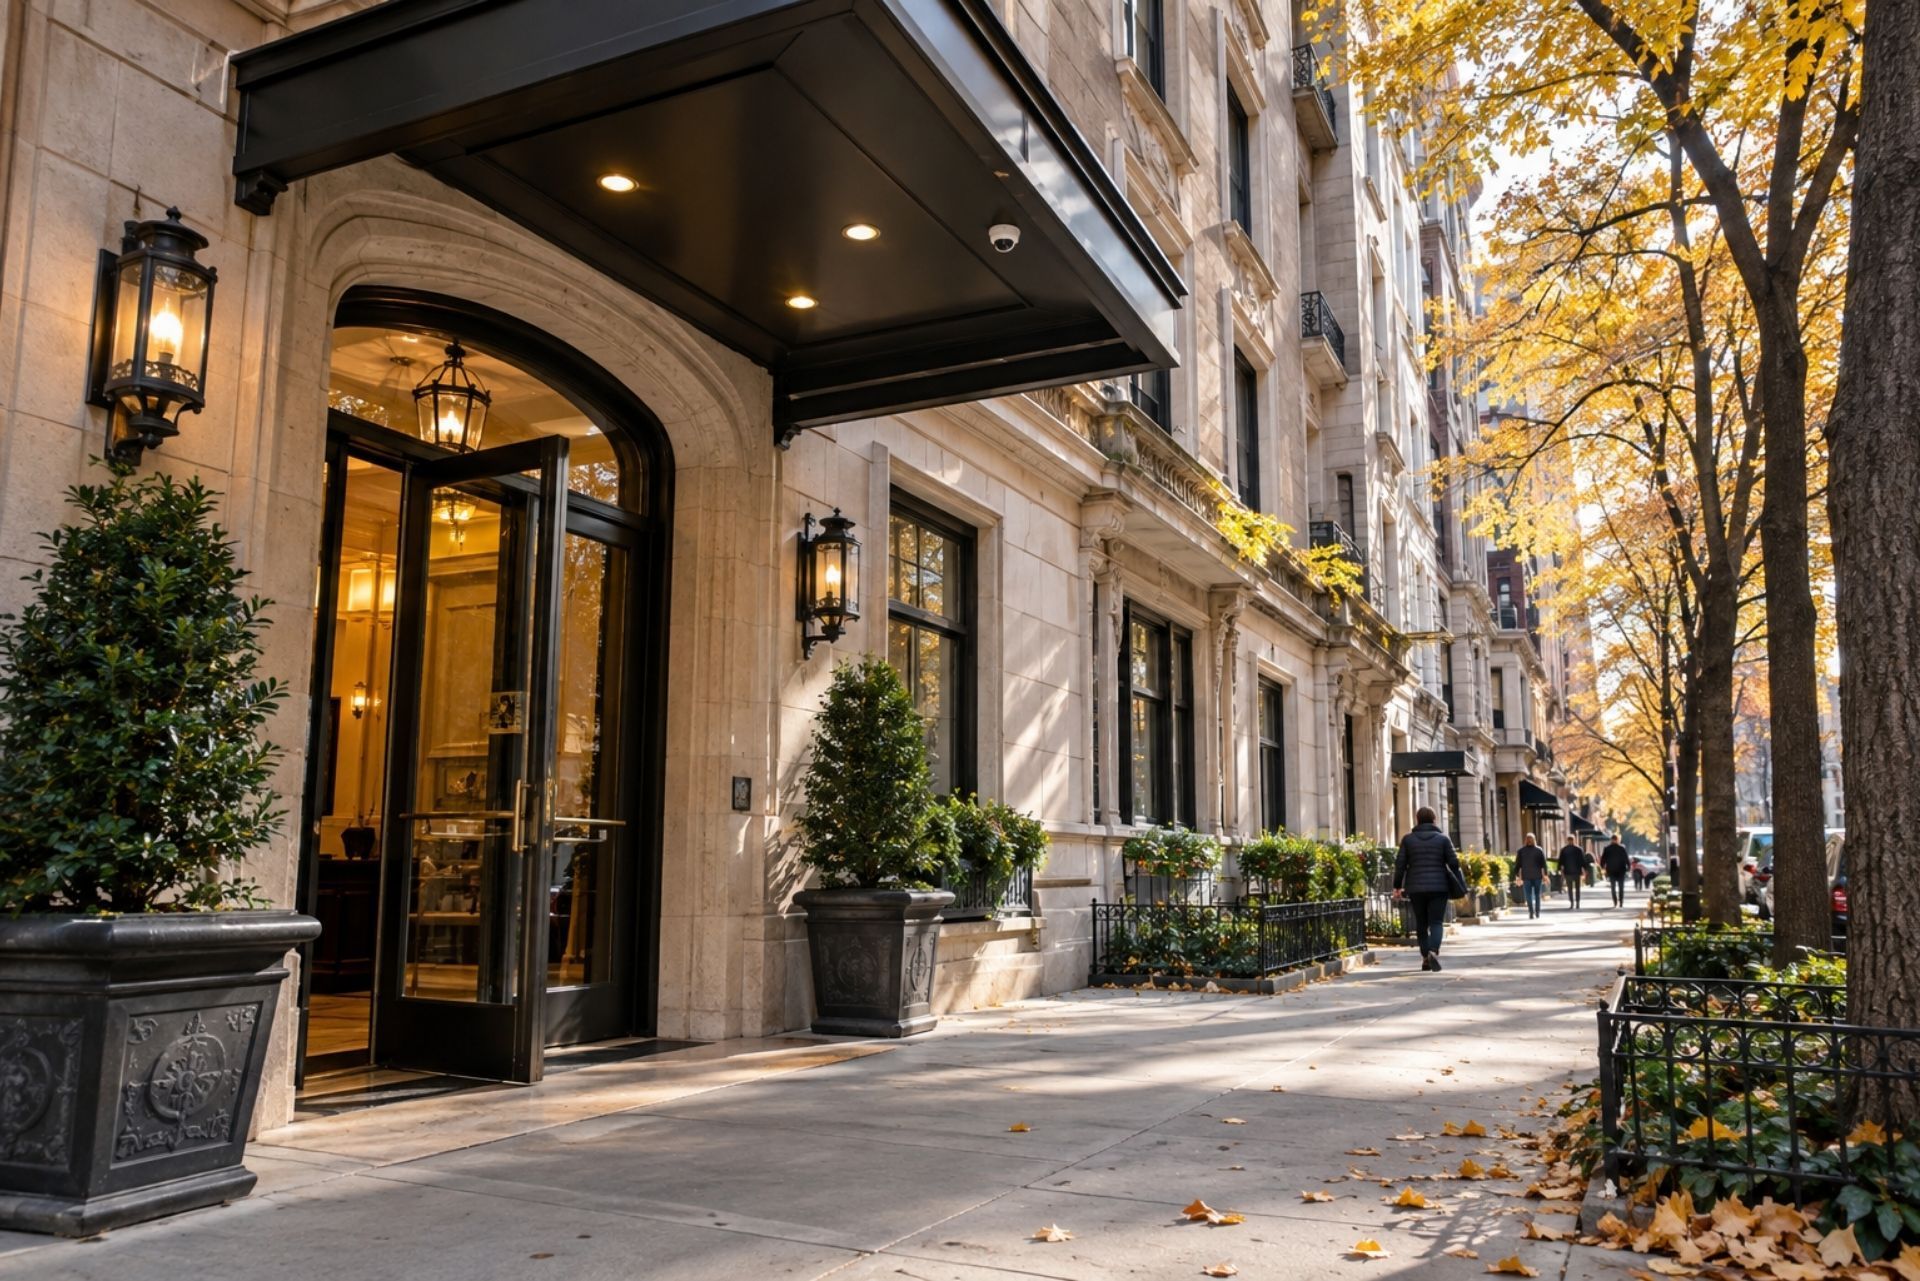
Water is the number-one source of claims in Upper East Side co-ops and condos. Prewar buildings, many dating to the 1920s and 1930s, have aging risers, original cast-iron drain lines, and plaster walls that act like sponges. A single incident can cascade through multiple floors.
UES boards are strictly enforcing "wet-over-dry" restrictions in 2026, prohibiting the relocation of kitchens or bathrooms over a neighbor's dry living areas. This rule exists because insurers have made it clear: buildings that don't control water risk will pay dramatically more for coverage, or lose it entirely.
Your personal policy should include water backup and sump overflow coverage. Make sure your policy doesn't exclude "gradual leaks," which is exactly the type of damage prewar plumbing causes. If your building requires you to install automatic water shutoff valves, do it: it may also earn you a premium discount.
Your premium isn't just about square footage. Insurers evaluate a matrix of building-level and unit-level factors that can swing your annual cost by hundreds of dollars.
Building Age and Pre-War Infrastructure Risks
A 1927 limestone co-op on Fifth Avenue carries different risk than a 2015 glass-curtain condo on Third. Older buildings mean older plumbing, older electrical, and older roofing. Insurers price that risk into your premium. If your building has had multiple water damage claims in the past five years, expect your personal policy to cost more too, because underwriters look at the building's claims history alongside yours.
Renovation History and Smart Home Security
Recent renovations can work in your favor, especially if you've replaced old plumbing or installed smart leak detectors. Buildings with centralized water monitoring systems are becoming more attractive to underwriters. On the flip side, if you've done unpermitted work or your alteration agreement is incomplete, that's a red flag that could complicate a future claim.
Common Questions About UES Apartment Insurance
Do I need insurance if my co-op's master policy already covers the building? Yes. The master policy covers the building structure and common areas. Your personal belongings, interior renovations, liability, and loss assessments require your own HO-6 policy.
How much liability coverage should I carry? Most insurance professionals recommend at least $500,000 in personal liability for UES apartments, plus a $1 million umbrella policy. A Manhattan umbrella policy typically costs between $675 and $850 annually, which is modest relative to the protection it provides.
Will my board reject my application if I don't have enough coverage? Many boards will. Co-op boards routinely reject purchase applications or renovation requests when the buyer's insurance certificate doesn't meet the building's minimums. Don't wait until closing week to sort this out.
Does my policy cover damage I cause to a neighbor's apartment? Your personal liability coverage should respond if you're legally responsible for damage to another unit, such as a leak originating from your bathroom. The neighbor would file against you, and your insurer would handle the defense and settlement up to your policy limit.
What's the difference between replacement cost and actual cash value?
Replacement cost pays to replace damaged items at current prices. Actual cash value deducts depreciation, meaning your 10-year-old sofa might only net you $200. Always choose replacement cost for personal property.
How Fannie Mae's 2026 Condo Review Changes Affect You
If you're buying or refinancing a condo, there's a major shift to know about. Effective August 3, 2026, Fannie Mae has eliminated "limited reviews" for established NYC condos, requiring a full review of building insurance, reserves, and litigation. That means your lender will scrutinize whether the building's master policy meets Fannie Mae's requirements, and any shortfall could delay or derail your mortgage.
This change makes your personal insurance even more important. If the building's coverage has gaps, your own policy is your backstop.
The Pied-à-Terre Tax and Insurance Implications
Starting July 1, 2026, a new NYC pied-à-terre tax applies a surcharge to non-primary residences valued over $1 million. If your UES apartment is a secondary residence, this tax adds to your carrying costs. It also raises an insurance question: policies for non-primary residences sometimes carry different terms, higher premiums, or vacancy exclusions. Confirm with your agent that your policy reflects how you actually use the apartment.
Steps to Review and Strengthen Your Current Policy
Pull out your declarations page right now and check three things. First, does your walls-in coverage reflect the actual cost of your renovations, not just the purchase price? Second, is your loss assessment limit above $25,000? Third, do you have water backup coverage with a limit that matches your risk?
If any answer is no, call your agent this week. Premiums are rising, and locking in better coverage now is smarter than scrambling after a claim.
Making the Right Choice for Your Home
Getting condo and co-op insurance right on the Upper East Side means understanding where your building's coverage ends and yours begins. That boundary is different in every building and shifts every time you renovate. The essentials: adequate walls-in coverage that reflects your actual finishes, loss assessment limits well above the default, personal liability of at least $500,000 with an umbrella on top, and explicit water damage protection.
Don't treat your policy as a set-it-and-forget-it line item. Review it annually, after every renovation, and whenever your board updates its requirements. The 2026 insurance market in NYC is volatile, with premiums climbing and underwriters tightening standards. Your best defense is a policy that's been reviewed by someone who knows prewar buildings, board requirements, and the specific risks of Upper East Side living. Reach out to a broker who specializes in NYC co-op and condo coverage, bring your board's insurance requirements, and build a policy that actually protects what you own.
ABOUT THE AUTHOR:
TAYLOR RICHARDSON
Taylor Richardson is the founder and CEO of 5M Insurance. With a focus on real estate risk management, Taylor helps investors and property managers nationwide secure smarter, scalable coverage solutions—without the headaches of traditional insurance brokers.
Contact Us
Comprehensive Coverage for Businesses of All Sizes
Protecting Your Business, Securing Your Future
General Liability Insurance
Protection against lawsuits and third-party claims.
Workers Comp Insurance
Required protection for employees in case of injury or illness.
Commercial Property Insurance
Coverage for buildings, equipment, and business assets.
Commercial Auto Insurance
Coverage for company vehicles and fleet operations.
Commercial Umbrella Insurance
Protection against errors, omissions, and negligence claims.
Business Owner's Policy
A bundled policy combining essential business coverages.
Personalized Insurance for Every Stage of Life
Protect What Matters Most with Comprehensive Coverage
Jewelry Insurance
Specialized protection for valuable items like engagement rings, watches, and heirlooms.
Pet Insurance
Financial protection for veterinary care and unexpected pet health expenses.
Specialized Insurance for Your Business Needs
Serving the Industries That Drive
New York & New Jersey
What Our Clients Say
Trusted by Businesses & Families Across New York & New Jersey
Frequently Asked Questions
Get Answers to Your Insurance Questions
We understand that insurance can be complex. Here are answers to some of the most common questions our clients ask. If you need more information, our team is always here to help.
- Still have questions?
How do I know what coverage I need?
Choosing the right insurance starts with understanding your risks. For personal insurance, consider factors like your home’s value, your vehicle, and your financial responsibilities. Homeowners may need additional protection for floods or valuable belongings, while drivers should evaluate coverage limits based on their assets.
For businesses, the right coverage depends on the industry, number of employees, and liability risks. General liability is essential for most businesses, but some may need property, workers’ compensation, or business owner’s policies. Our team can assess your needs and guide you to the best options.
What factors affect my insurance rate?
Insurance rates are influenced by multiple factors. For auto policies, your driving history, vehicle type, and location play a major role. Home insurance costs depend on your home’s value, construction type, and potential risks like flooding or fire hazards.
For business insurance, rates vary based on the industry, size, claims history, and coverage limits. High-risk industries may require specialized policies, while businesses with strong safety measures and claims-free histories can qualify for better rates. Our agents help find discounts and cost-saving opportunities.
Why should I work with an independent insurance agency?
Unlike captive agents who represent a single insurance company, independent agencies like Joyce Insurance Agency work with multiple carriers to find the best coverage for your needs. This means you get more choices, competitive rates, and a policy that truly fits your situation.
We take the time to understand your needs, compare options, and provide expert advice. Whether you're insuring your home, car, or business, our priority is finding you the best protection at a great value.
How quickly can I get insured?
The time it takes to secure a policy depends on the type of insurance. Auto and home policies can often be issued the same day, while business insurance may take longer, especially for specialized coverage. Workers’ compensation and commercial policies may require underwriting approval, which can extend the timeline.
We prioritize efficiency and make the process as smooth as possible. Once we understand your needs, we work quickly to get you insured with minimal hassle.
What should I do if I need to file a claim?
If you need to file a claim, contact us as soon as possible. We’ll guide you through the process and ensure you have everything needed to submit your claim correctly. Gathering necessary documentation, such as photos, receipts, or witness statements, can help speed up the process.
We work directly with your insurance provider to streamline communication and advocate on your behalf. Our goal is to make sure your claim is handled quickly and fairly so you can recover without unnecessary stress.
How can I lower my insurance costs?
There are several ways to reduce insurance premiums without sacrificing coverage. For auto insurance, maintaining a clean driving record, bundling policies, and increasing deductibles can help lower costs. Homeowners can save by installing security systems, upgrading safety features, and bundling home and auto policies.
For business owners, implementing risk management strategies, maintaining a claims-free history, and working with an independent agent to find competitive rates can lead to cost savings. Our team helps you explore discounts and options to ensure you’re getting the best value.
Contact Us
Phone
Location