
A burst pipe on the 14th floor of a Chelsea high-rise doesn't just ruin one unit. It cascades through ceilings, walls, and floors, leaving a trail of damage that your condo association's master policy won't fully cover. If you own a condo in Chelsea, Manhattan, your
HO-6 policy is the single most important financial safeguard between you and a six-figure out-of-pocket loss. This guide breaks down walls-in coverage, flood risk from the Hudson River, water damage claims, loss assessments, and personal liability so you can protect your investment with the right policy. The NYC condo insurance market is tightening fast in 2026, with
premium increases exceeding 20% and fewer carriers offering coverage in many buildings. Understanding what you need before renewal season hits can save you thousands and prevent dangerous gaps. Whether you're in a converted warehouse on West 19th or a glass tower near the High Line, your risks are specific to this neighborhood, and your coverage should be too.
Understanding HO-6 Insurance for Chelsea Condo Owners
An HO-6 policy is the standard condo unit-owner's insurance form. It covers everything from the drywall inward: your personal belongings, interior finishes, fixtures, appliances, and liability. Think of it as the missing piece that fills the gap between your association's master policy and your actual financial exposure.
Chelsea's building stock ranges from pre-war conversions to brand-new luxury developments, and each building's master policy draws the line between "building responsibility" and "owner responsibility" differently. Your HO-6 policy needs to pick up exactly where that master policy stops.
Walls-In Coverage vs. Master Policy Responsibilities
Your condo association carries a master policy that typically covers the building's structure, common areas, and shared systems like elevators and boilers. But the definition of "unit" varies. Some master policies are "bare walls," meaning they cover only the original structural components. Others are "all-in" or "single entity" policies that include original fixtures and finishes.
You need to read your building's governing documents carefully. If your master policy is bare walls, your HO-6 must cover flooring, cabinetry, countertops, bathroom fixtures, and appliances. If it's all-in, you still need coverage for any upgrades or renovations you've made. Misunderstanding this boundary is one of the most common and costly mistakes Chelsea condo owners make.
Why Manhattan Co-ops and Condos Require Specific Riders
Standard HO-6 policies have built-in sublimits that fall short in Manhattan. Jewelry and fine art, for example, are often capped at $1,500 to $5,000 under standard policies, which barely covers a single piece in many Chelsea households. You'll need scheduled personal property riders to insure individual high-value items at their appraised value.
Many Chelsea buildings also require minimum liability limits, often $300,000 or $500,000, as a condition of ownership. Some boards mandate loss assessment coverage at specific thresholds. Check your proprietary lease or condo bylaws before shopping for a policy, because your building may dictate minimums that exceed what a basic HO-6 provides.
Core Coverage Components for Luxury Urban Living
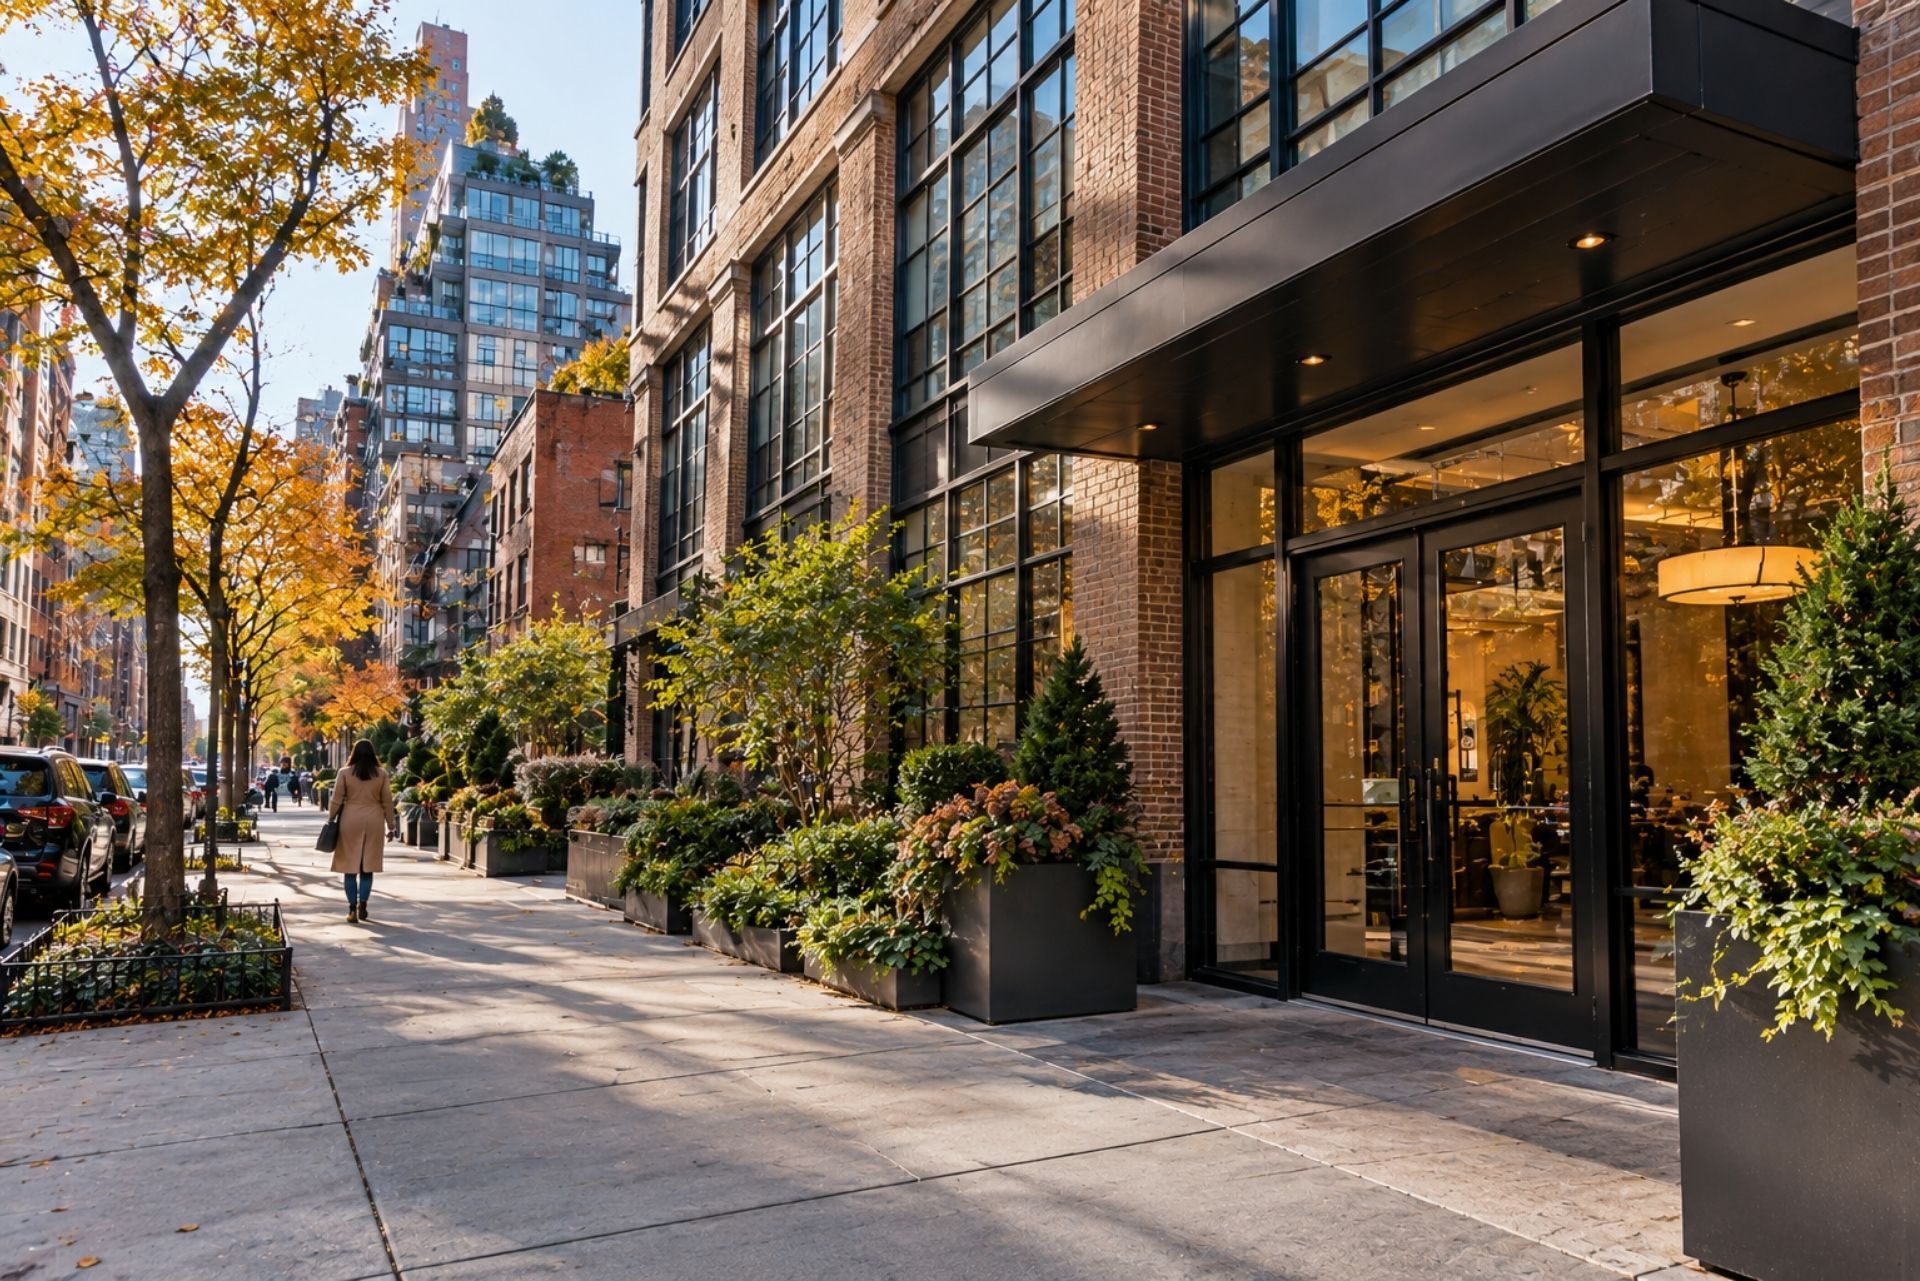
Chelsea condos aren't cookie-cutter apartments. Between custom kitchens, designer bathrooms, and smart-home systems, the interior of a typical Chelsea unit can be worth far more than the base dwelling coverage on a standard policy. Your HO-6 needs to reflect what you've actually built inside those walls.
Protecting High-End Renovations and Built-ins
If you've renovated your unit, your coverage amount for dwelling improvements should match the full replacement cost of those upgrades. A gut renovation in Chelsea can easily run $300 to $500 per square foot. A 1,200-square-foot unit with a high-end renovation could require $400,000 or more in dwelling improvement coverage alone.
Don't rely on estimates. Get a written replacement cost appraisal from a contractor familiar with Manhattan construction pricing. Material costs and labor rates in NYC are significantly higher than national averages, and your insurer will pay based on what it actually costs to rebuild, not what you think it might cost.
Personal Liability in High-Density Buildings
Living in a high-density building means your liability exposure is amplified. If a guest slips on your wet bathroom floor, if your dog bites a neighbor in the hallway, or if a water leak from your unit damages units below you, your personal liability coverage responds first.
Most HO-6 policies start at $100,000 in liability coverage, but that's dangerously low for a Manhattan condo owner. Aim for at least $300,000 to $500,000 in your base policy, and seriously consider a personal umbrella policy on top of that. Carriers are increasingly requiring proof of specific net worth for umbrella policies above $5 million, so plan your coverage tower carefully.
Loss Assessment: A Chelsea Essential
Here's a scenario that catches owners off guard every year. Your building suffers a major loss, like a lobby flood or roof collapse, and the master policy's deductible is $250,000. The board divides that deductible among all unit owners. Suddenly you owe $10,000 or $25,000 as a special assessment.
Loss assessment coverage on your HO-6 policy pays your share of these assessments. Standard policies include $1,000 in loss assessment coverage, which is laughably inadequate for a Chelsea building. You should carry at least $50,000, and $100,000 isn't unreasonable given the size of commercial master policy deductibles in Manhattan.
Comparing Standard vs. Enhanced Condo Policies
Not all HO-6 policies are created equal. The difference between a standard and enhanced policy can mean the difference between a fully covered claim and a devastating gap. Here's how they compare on the coverage elements that matter most in Chelsea.
Coverage Comparison Table
| Coverage Element | Standard HO-6 | Enhanced HO-6 |
|---|---|---|
| Dwelling Improvements | $50,000 - $100,000 | $250,000 - $500,000+ |
| Personal Property | Actual Cash Value | Replacement Cost |
| Jewelry/Art Sublimit | $1,500 - $5,000 | Scheduled, appraised value |
| Loss Assessment | $1,000 | $50,000 - $100,000 |
| Liability | $100,000 | $300,000 - $500,000 |
| Water Backup | Not included | $25,000 - $50,000 |
| Flood | Not included | Separate policy required |
| Ordinance/Law | Not included | 10% - 25% of dwelling coverage |
The "ordinance or law" line is worth your attention. If a covered loss triggers a renovation, NYC building codes may require upgrades beyond the original construction. Without ordinance or law coverage, you pay for those code-mandated upgrades yourself.
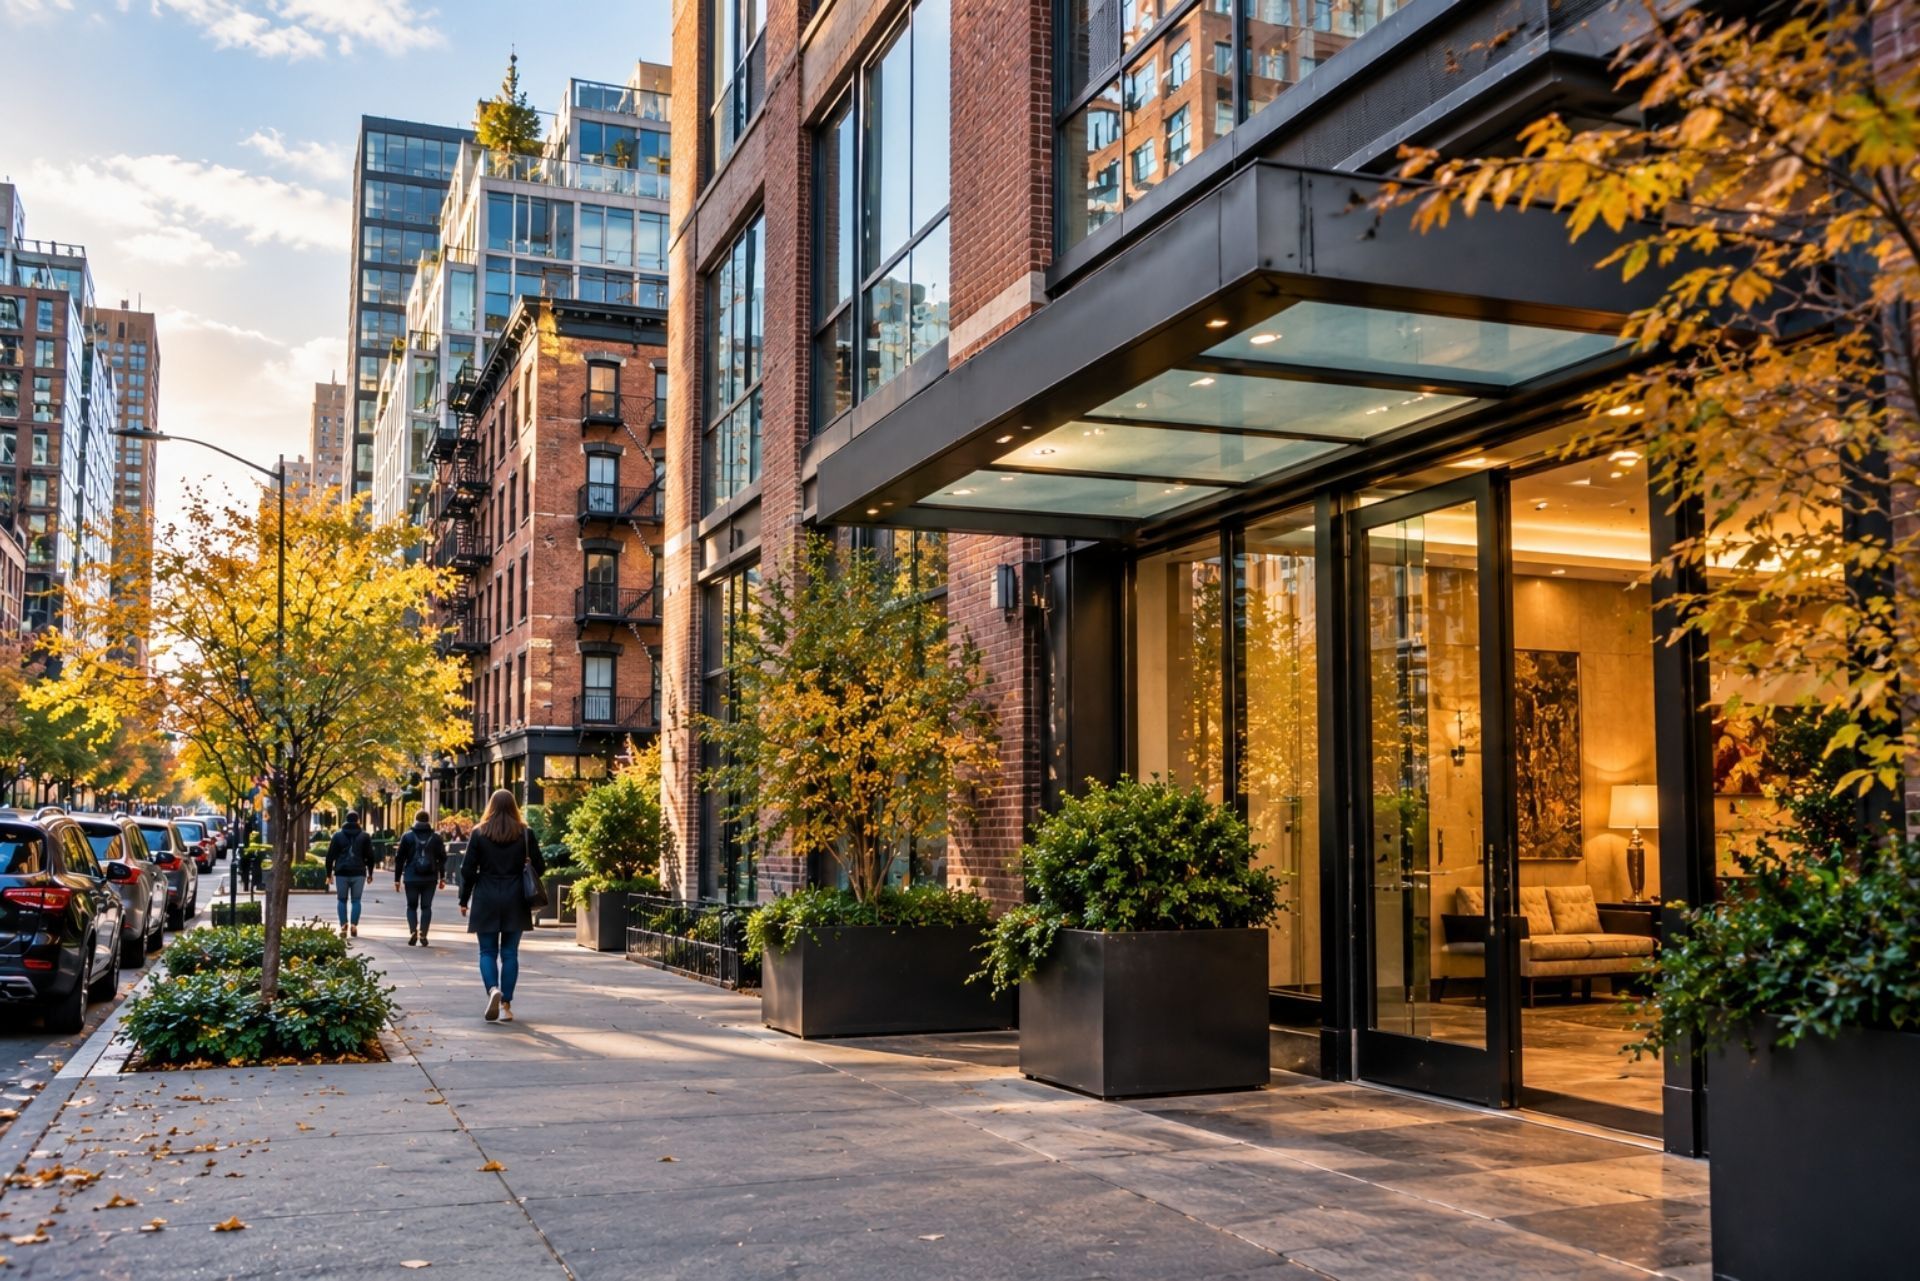
The average annual cost for condo insurance in New York City sits around $3,080, but your actual premium depends heavily on building-specific and unit-specific factors. Chelsea's mix of old and new construction creates a wide range of risk profiles.
Building Age and Plumbing Systems
Underwriters in 2026 are scrutinizing building maintenance and infrastructure more aggressively than ever. A pre-war Chelsea building with original cast-iron plumbing presents a very different risk than a 2015 new-development with PEX piping. Older plumbing systems are the number-one driver of water damage claims in Manhattan condos.
If your building has recently replaced its risers or upgraded its plumbing, make sure your broker communicates that to underwriters. It can meaningfully reduce your premium. On the flip side, buildings with a history of water damage claims may face surcharges or limited carrier options.
Security Features and Concierge Services
Buildings with 24-hour doormen, security cameras, and controlled access generally earn lower premiums. These features reduce theft and liability risk. Smart-home technology matters at the unit level too: installing smart water shutoff valves can earn premium credits of 5% to 15%, which adds up quickly on a Manhattan-sized premium.
Sprinkler systems, fire alarms tied to a central monitoring station, and backup generators also factor into your rate. If your building has these features, confirm that your insurer has them on file. Missing credits are surprisingly common.
Chelsea properties south of West 23rd Street face particular flood exposure. These blocks sit at base flood elevations of only 2 to 4 feet above grade, making them vulnerable during major storm events. Standard HO-6 policies exclude flood damage entirely, so you'll need a separate flood policy through the NFIP or a private flood carrier if you're in or near a FEMA-designated flood zone.
Common Questions About Chelsea Condo Insurance
Do I need condo insurance if my building has a master policy? Yes, always. The master policy covers the building's structure and common areas, not your personal belongings, interior finishes, or liability. Your HO-6 fills that critical gap.
Does my HO-6 cover water damage from a neighbor's unit above me? It depends on the cause. If a pipe bursts in the unit above and damages your ceiling and walls, your HO-6 typically covers your repairs. You'd then pursue the neighbor's liability coverage for reimbursement. Water backup coverage is a separate endorsement you should add.
How much loss assessment coverage do I actually need? For Chelsea buildings, $50,000 is a reasonable starting point. Buildings with high master policy deductibles or aging infrastructure may warrant $100,000. Ask your board what the master policy deductible is before deciding.
Is flood insurance required for Chelsea condos? If you have a mortgage and your unit is in a FEMA-designated flood zone, your lender will require it. Even if it's not required, owners near the Hudson River or in low-lying areas south of 23rd Street should seriously consider it.
Can I bundle my condo insurance with other policies? Yes, and bundling with auto or umbrella policies often yields discounts. Ask your broker about multi-policy options.
What's the difference between replacement cost and actual cash value? Replacement cost pays what it costs to replace your item new. Actual cash value deducts depreciation, meaning your five-year-old sofa might only be worth a fraction of its replacement. Always choose replacement cost for personal property.
Making the Right Choice for Your Property
Your Chelsea condo is likely one of your largest financial commitments. The right HO-6 policy protects not just your belongings but your renovations, your liability exposure, and your share of building-wide losses. Getting this wrong can cost tens of thousands of dollars in a single claim.
Start by requesting a copy of your building's master policy and insurance requirements from the managing agent. Identify the coverage boundary, whether it's bare walls or all-in. Then work with a broker who specializes in Manhattan condo insurance to build a policy that matches your actual exposure: your renovation costs, your personal property values, your liability needs, and your flood risk.
Don't wait for a renewal notice to review your coverage. Pull your policy out now, compare it against the enhanced coverage benchmarks in this guide, and close any gaps before the next nor'easter or pipe burst makes the decision for you. A 30-minute conversation with the right broker today can prevent a catastrophic financial loss tomorrow.
ABOUT THE AUTHOR:
TAYLOR RICHARDSON
Taylor Richardson is the founder and CEO of 5M Insurance. With a focus on real estate risk management, Taylor helps investors and property managers nationwide secure smarter, scalable coverage solutions—without the headaches of traditional insurance brokers.
Contact Us
Comprehensive Coverage for Businesses of All Sizes
Protecting Your Business, Securing Your Future
General Liability Insurance
Protection against lawsuits and third-party claims.
Workers Comp Insurance
Required protection for employees in case of injury or illness.
Commercial Property Insurance
Coverage for buildings, equipment, and business assets.
Commercial Auto Insurance
Coverage for company vehicles and fleet operations.
Commercial Umbrella Insurance
Protection against errors, omissions, and negligence claims.
Business Owner's Policy
A bundled policy combining essential business coverages.
Personalized Insurance for Every Stage of Life
Protect What Matters Most with Comprehensive Coverage
Jewelry Insurance
Specialized protection for valuable items like engagement rings, watches, and heirlooms.
Pet Insurance
Financial protection for veterinary care and unexpected pet health expenses.
Specialized Insurance for Your Business Needs
Serving the Industries That Drive
New York & New Jersey
What Our Clients Say
Trusted by Businesses & Families Across New York & New Jersey
Frequently Asked Questions
Get Answers to Your Insurance Questions
We understand that insurance can be complex. Here are answers to some of the most common questions our clients ask. If you need more information, our team is always here to help.
- Still have questions?
How do I know what coverage I need?
Choosing the right insurance starts with understanding your risks. For personal insurance, consider factors like your home’s value, your vehicle, and your financial responsibilities. Homeowners may need additional protection for floods or valuable belongings, while drivers should evaluate coverage limits based on their assets.
For businesses, the right coverage depends on the industry, number of employees, and liability risks. General liability is essential for most businesses, but some may need property, workers’ compensation, or business owner’s policies. Our team can assess your needs and guide you to the best options.
What factors affect my insurance rate?
Insurance rates are influenced by multiple factors. For auto policies, your driving history, vehicle type, and location play a major role. Home insurance costs depend on your home’s value, construction type, and potential risks like flooding or fire hazards.
For business insurance, rates vary based on the industry, size, claims history, and coverage limits. High-risk industries may require specialized policies, while businesses with strong safety measures and claims-free histories can qualify for better rates. Our agents help find discounts and cost-saving opportunities.
Why should I work with an independent insurance agency?
Unlike captive agents who represent a single insurance company, independent agencies like Joyce Insurance Agency work with multiple carriers to find the best coverage for your needs. This means you get more choices, competitive rates, and a policy that truly fits your situation.
We take the time to understand your needs, compare options, and provide expert advice. Whether you're insuring your home, car, or business, our priority is finding you the best protection at a great value.
How quickly can I get insured?
The time it takes to secure a policy depends on the type of insurance. Auto and home policies can often be issued the same day, while business insurance may take longer, especially for specialized coverage. Workers’ compensation and commercial policies may require underwriting approval, which can extend the timeline.
We prioritize efficiency and make the process as smooth as possible. Once we understand your needs, we work quickly to get you insured with minimal hassle.
What should I do if I need to file a claim?
If you need to file a claim, contact us as soon as possible. We’ll guide you through the process and ensure you have everything needed to submit your claim correctly. Gathering necessary documentation, such as photos, receipts, or witness statements, can help speed up the process.
We work directly with your insurance provider to streamline communication and advocate on your behalf. Our goal is to make sure your claim is handled quickly and fairly so you can recover without unnecessary stress.
How can I lower my insurance costs?
There are several ways to reduce insurance premiums without sacrificing coverage. For auto insurance, maintaining a clean driving record, bundling policies, and increasing deductibles can help lower costs. Homeowners can save by installing security systems, upgrading safety features, and bundling home and auto policies.
For business owners, implementing risk management strategies, maintaining a claims-free history, and working with an independent agent to find competitive rates can lead to cost savings. Our team helps you explore discounts and options to ensure you’re getting the best value.
Contact Us
Phone
Location